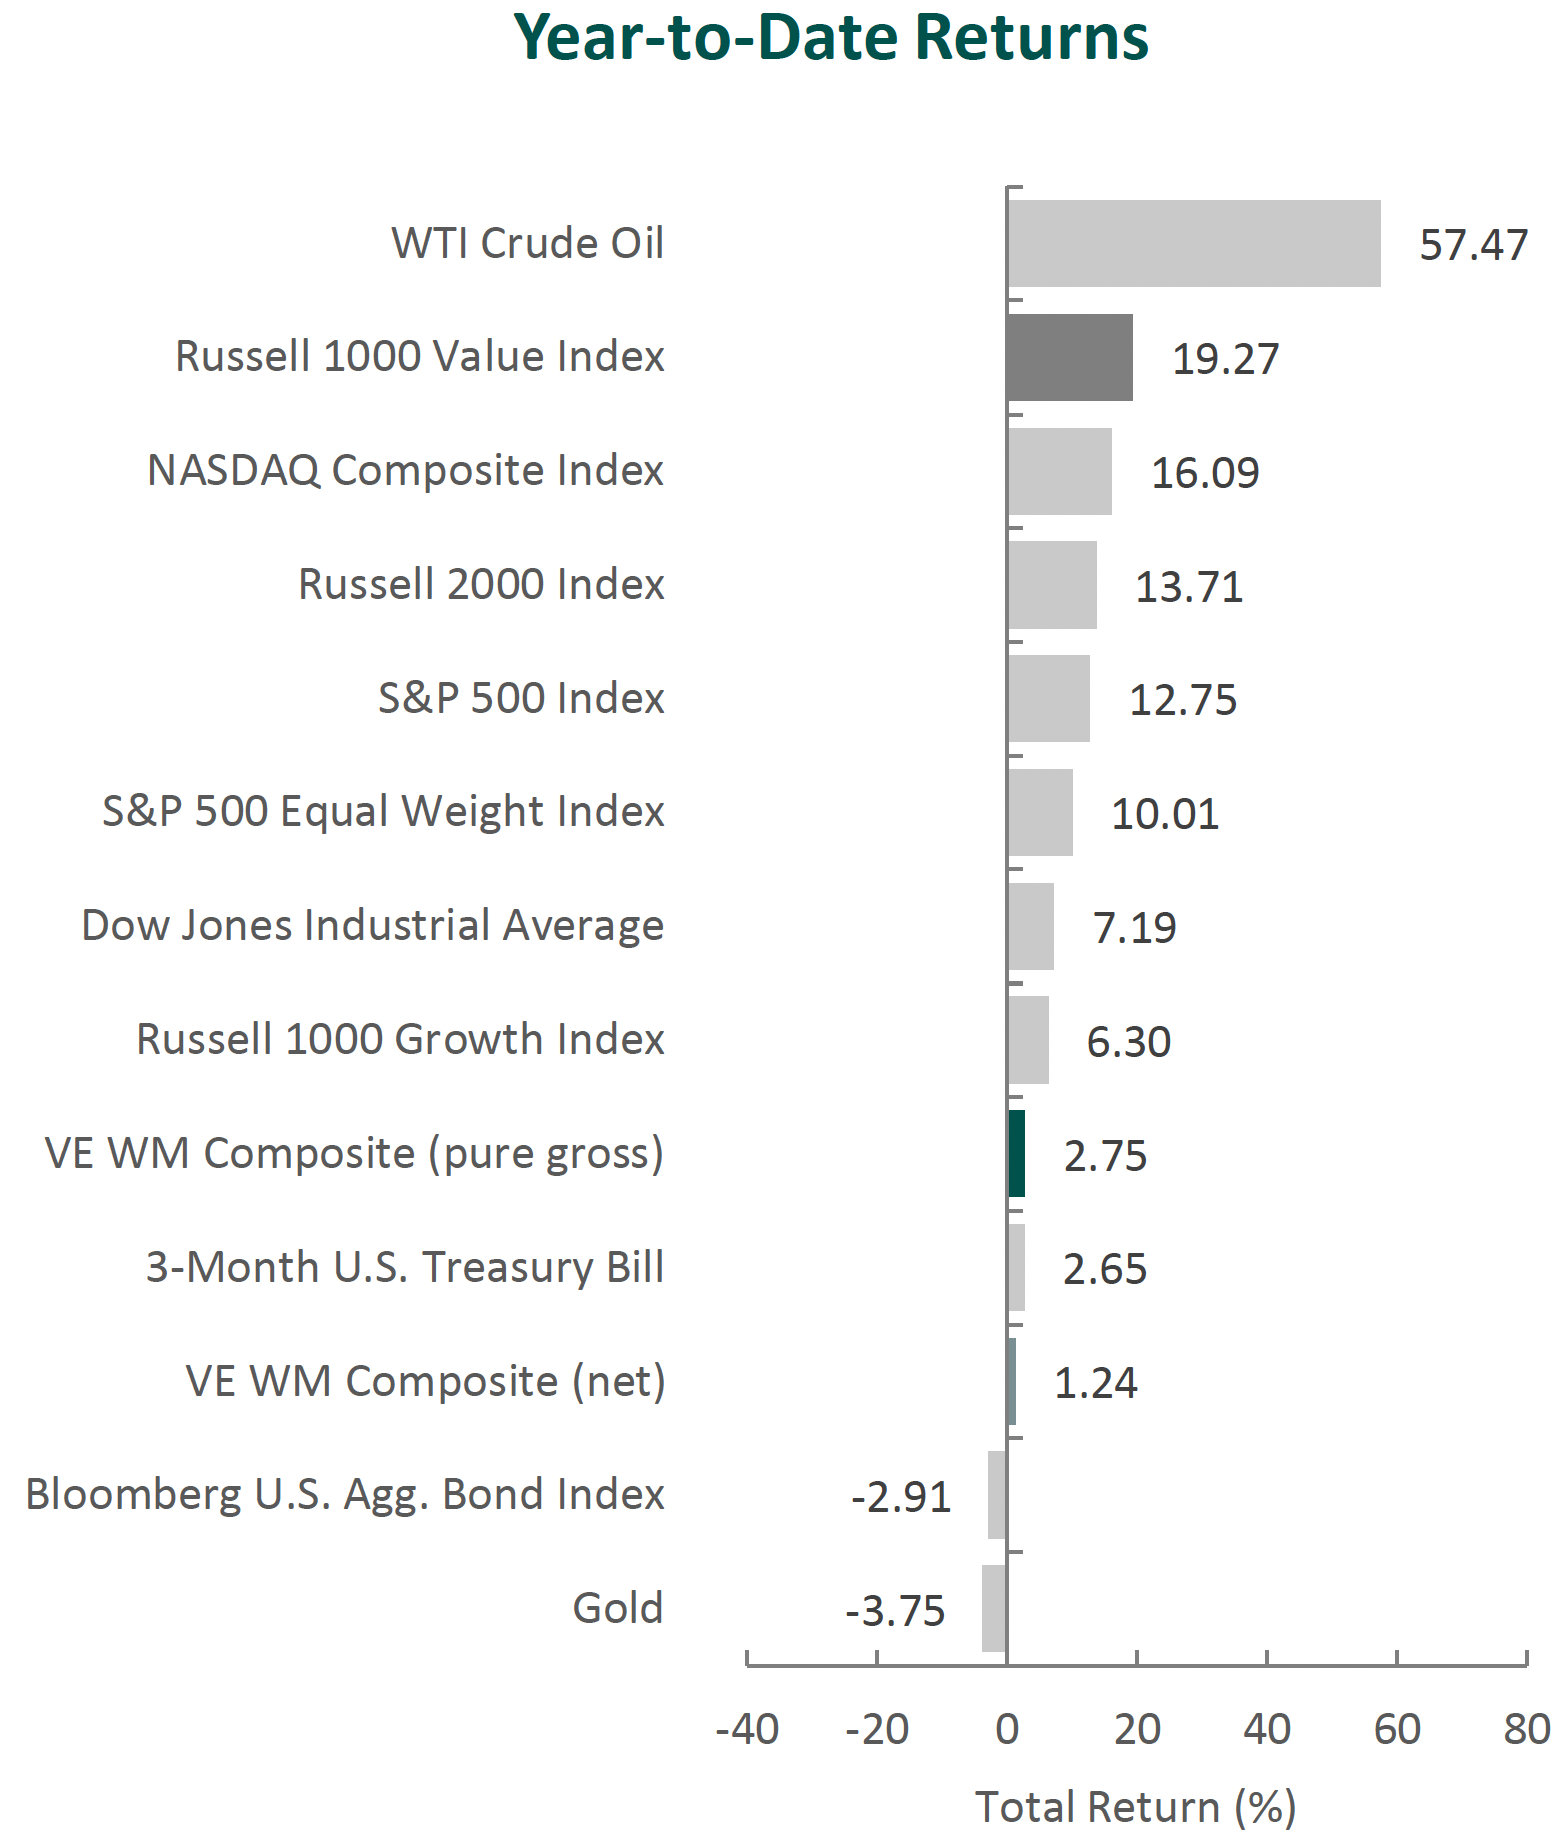


(All MSCI index returns are shown net and in U.S. dollars unless otherwise noted.)
Markets Review
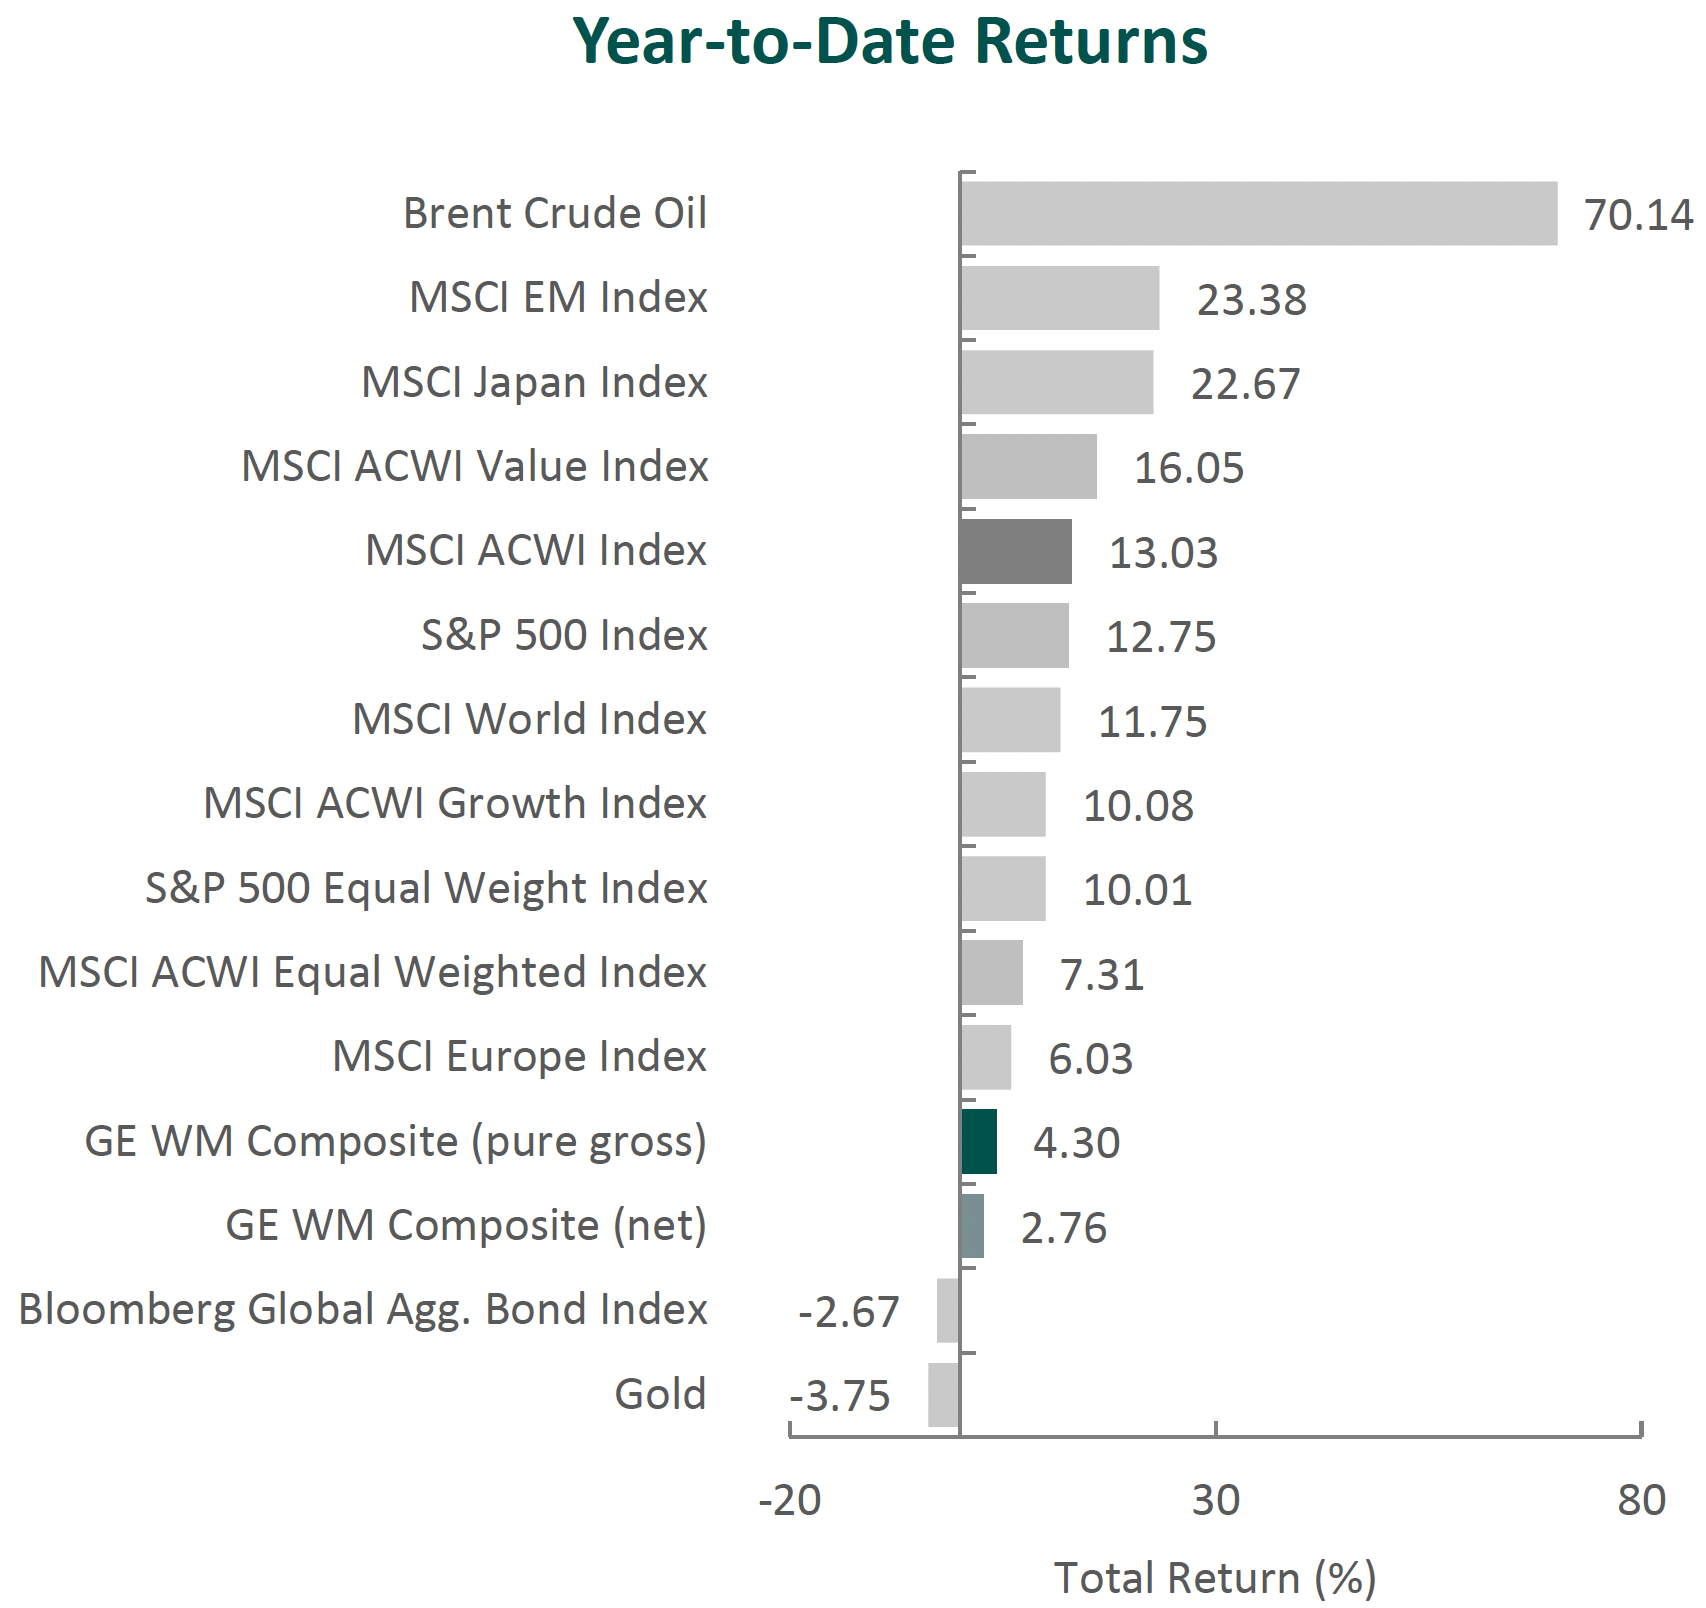
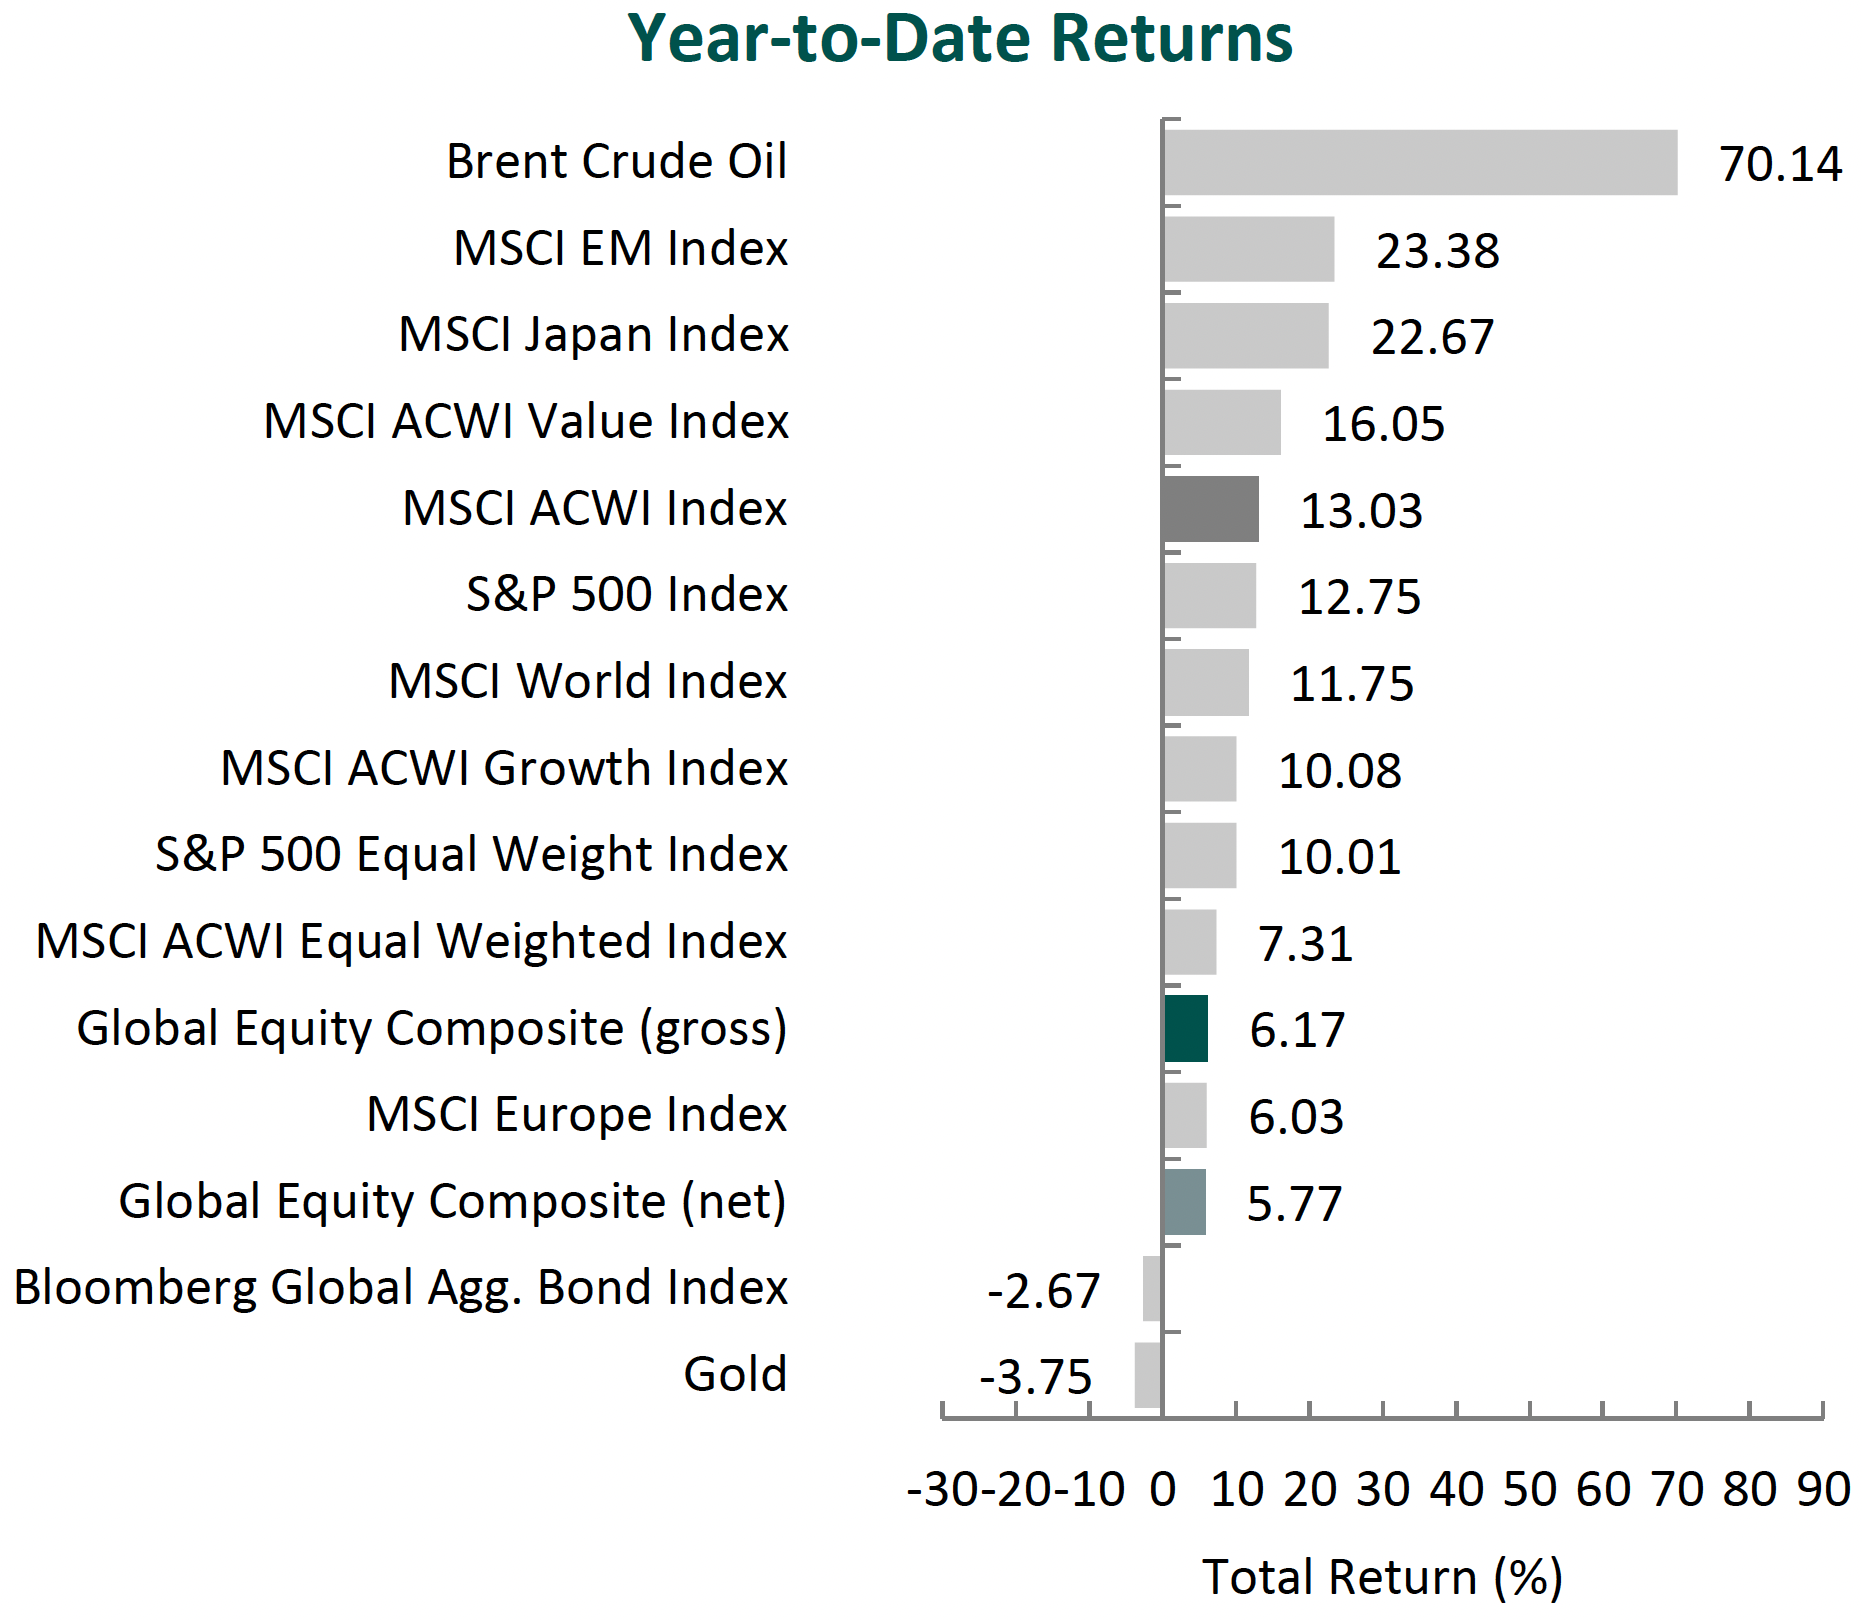
Sources: CAPS CompositeHubTM, Bloomberg
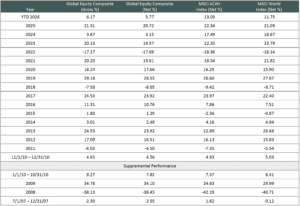
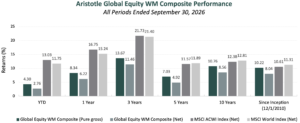
Past performance is not indicative of future results. Aristotle Global Equity WM Composite returns are presented pure gross and net of maximum wrap fee and include the reinvestment of income. Pure gross returns do not reflect the deduction of any trading costs or other fees and are supplemental to the net returns. Net returns are calculated by subtracting the highest applicable wrap/SMA fee, which includes trading costs and custodial fees, from the pure gross composite return. The highest applicable wrap/SMA fee is 2.00% on an annual basis, or 0.50% quarterly from inception to 12/31/2023 and 0.17% monthly from 1/1/2024 to present. Please see important disclosures at the end of this document.
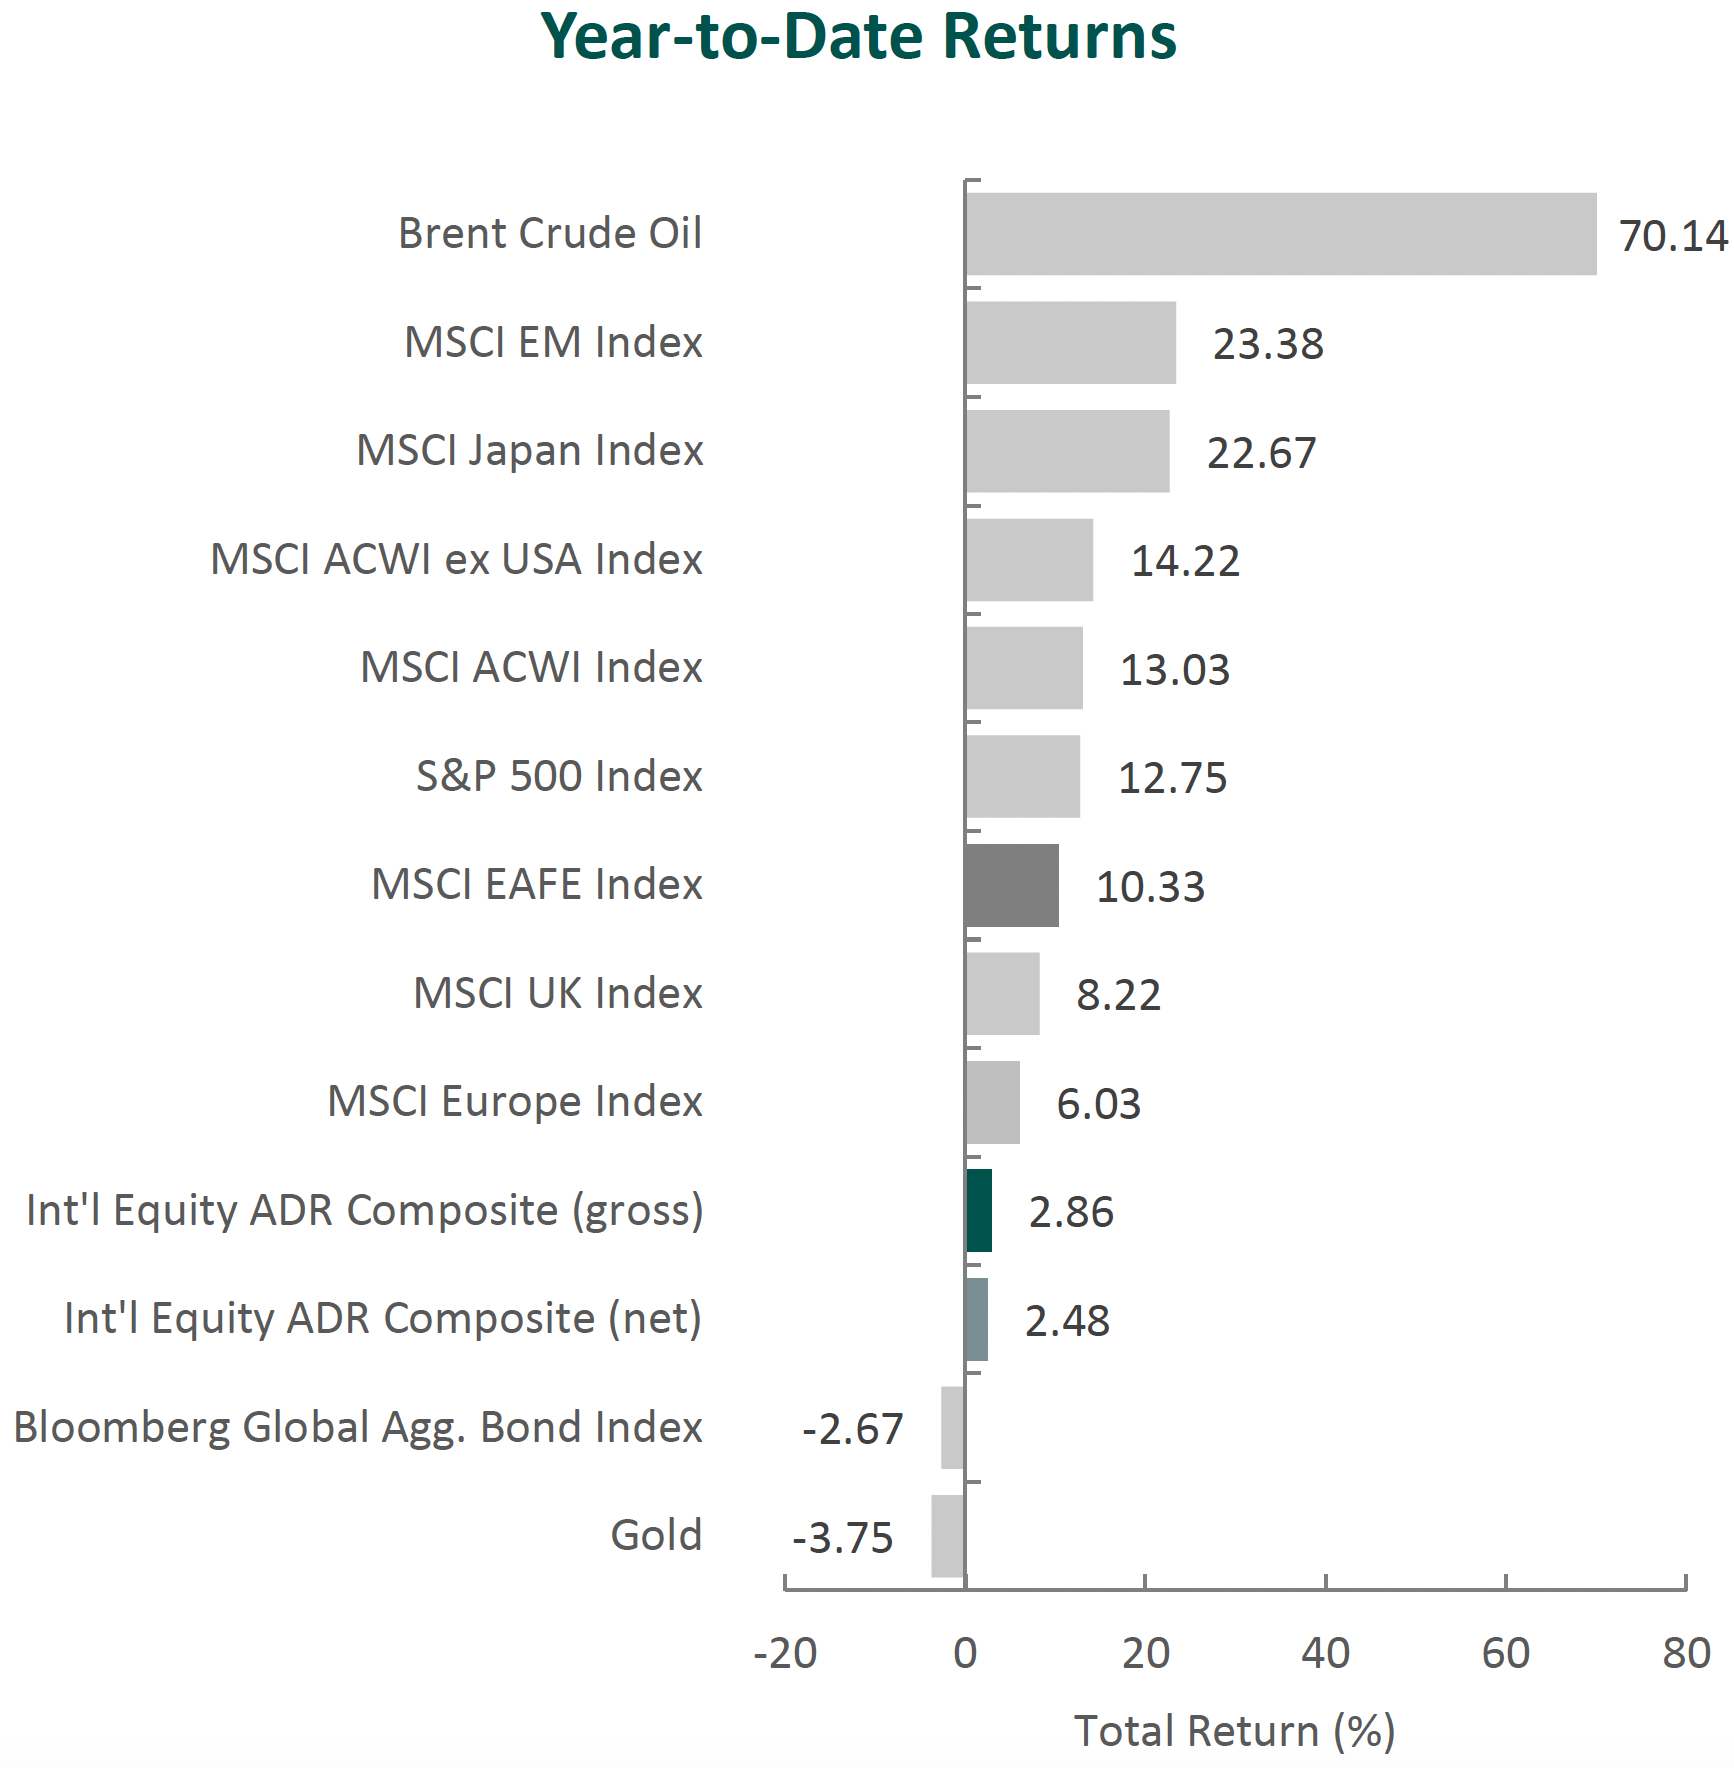
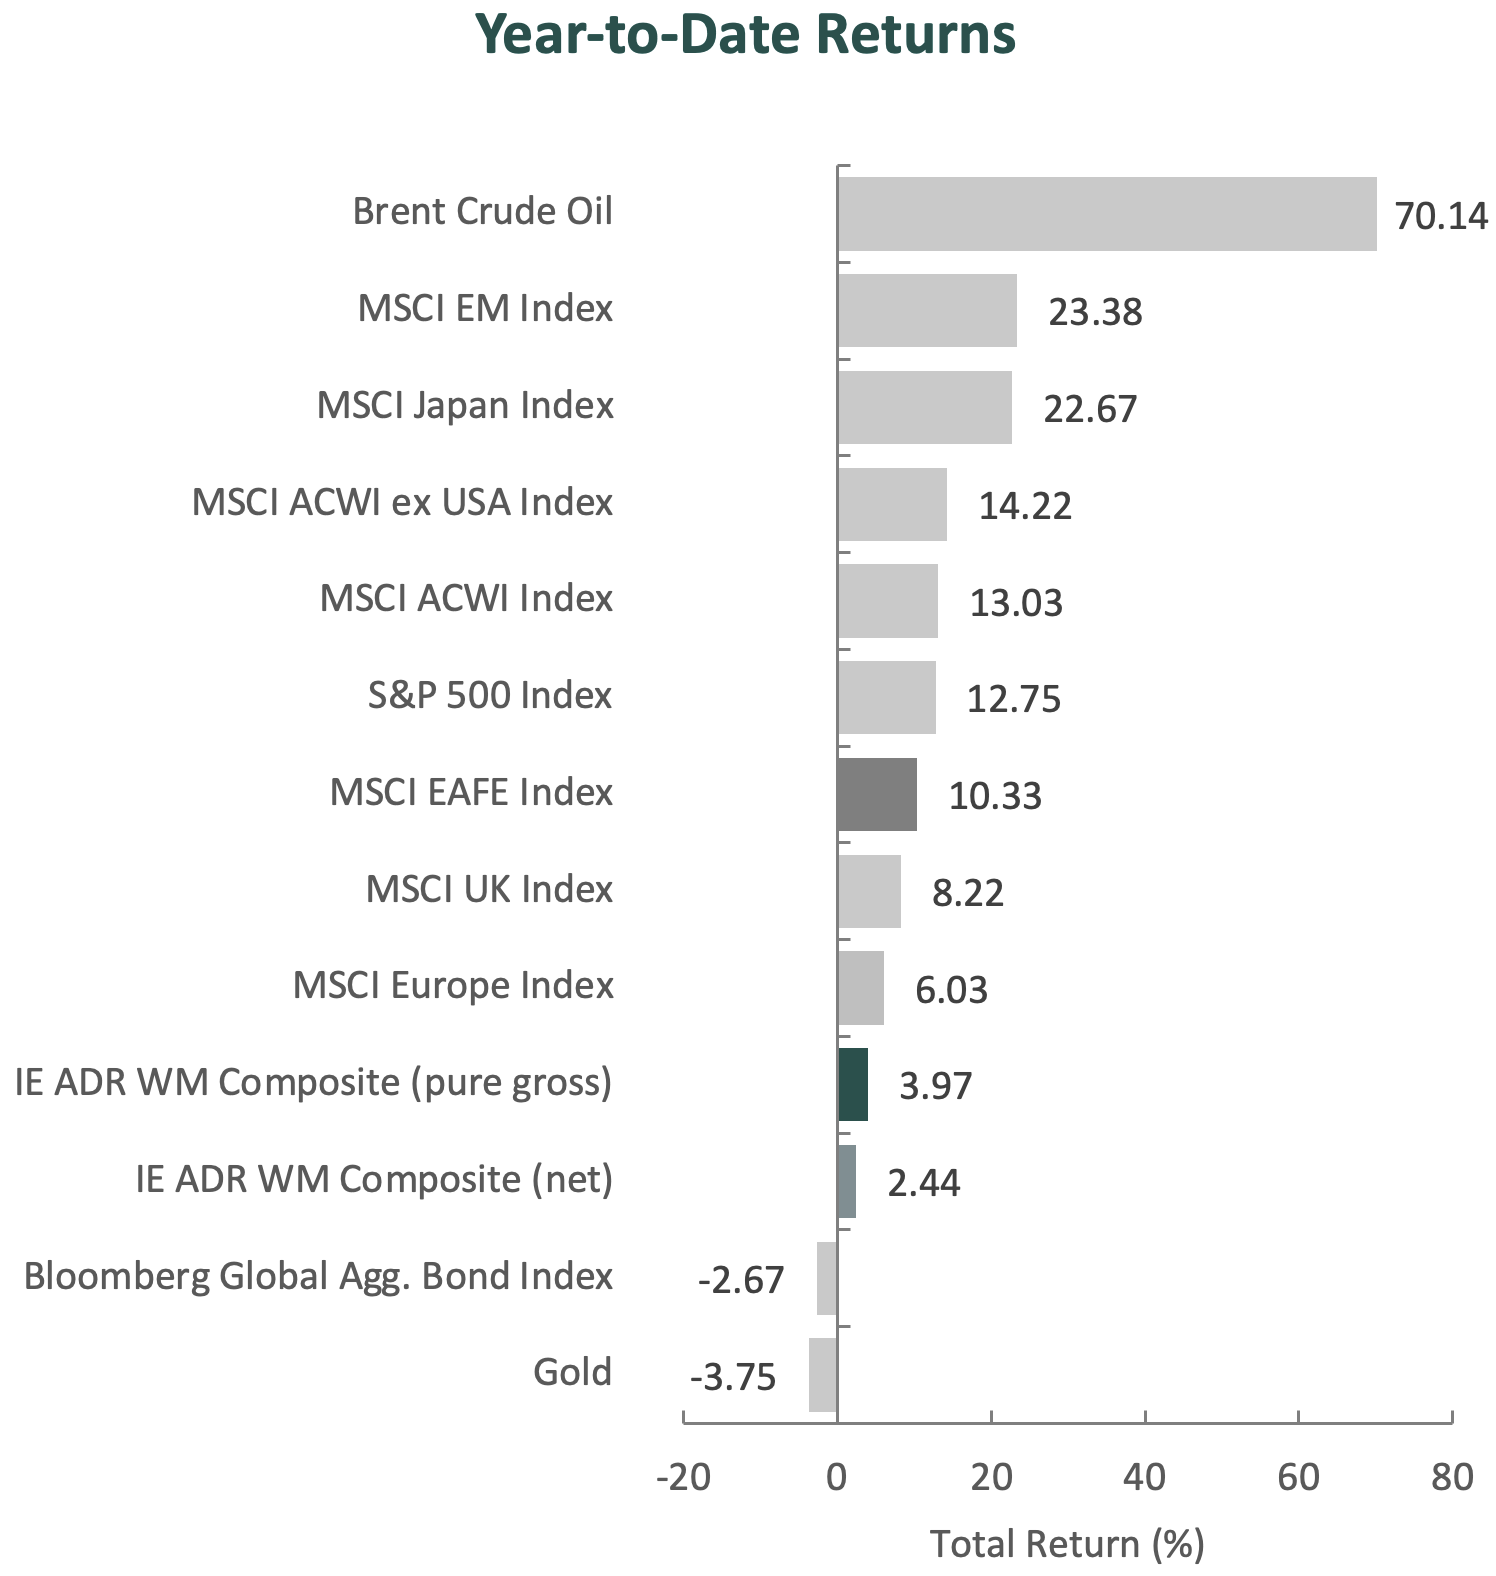
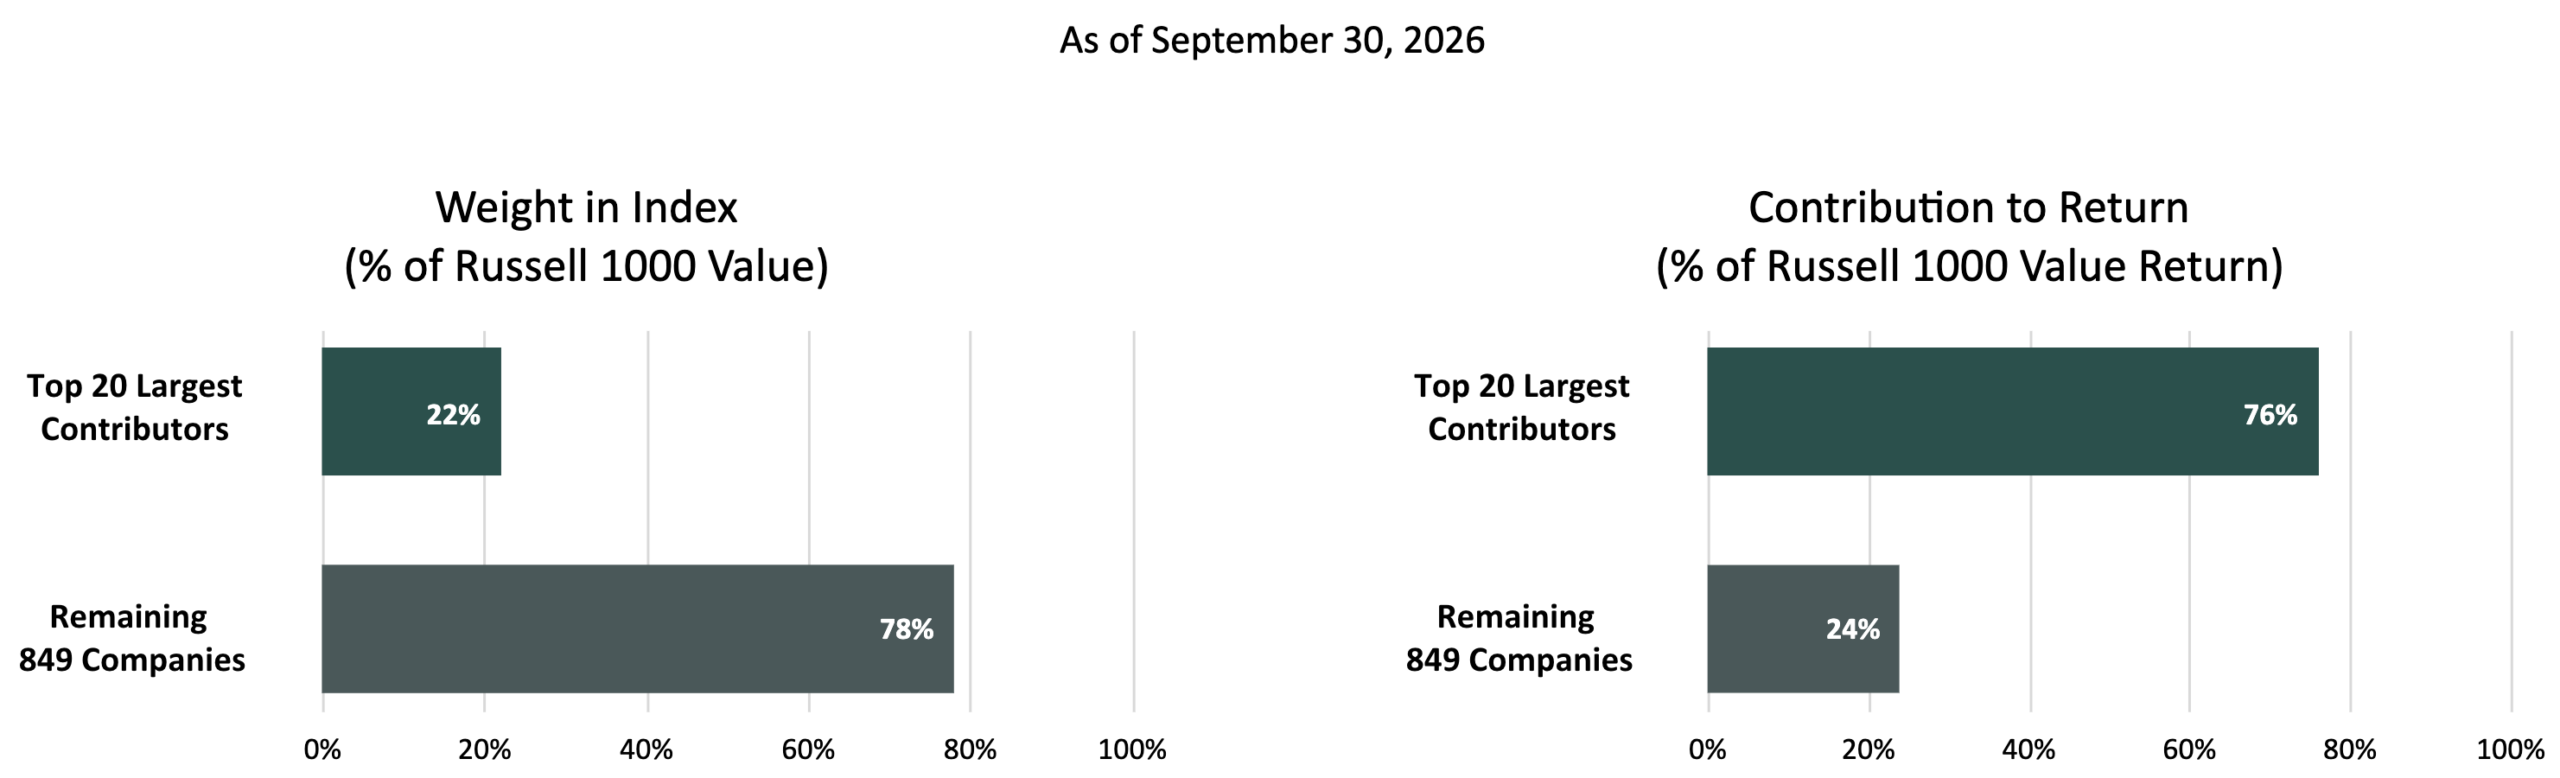
Shocks to energy prices stemming from renewed conflict in the Middle East, changing interest rate expectations, trade tensions, and enthusiasm (and fear) surrounding artificial intelligence (even among companies outside the United States) have become recurring themes of the market environment. Though global equity markets continue to climb, macroeconomic headlines seem to draw investors toward certain industries and away from others regardless of business fundamentals.
Brent crude, for example, started the year at roughly $60 per barrel and nearly doubled by May, then dropped back to ~$70 in July, only to spike back up above $100 later in the third quarter. Turning to central bank policy, following an unprecedented tightening cycle that concluded in 2023, the U.S. Federal Reserve cut interest rates six times in 2024 and 2025 before reversing course in the most recent quarter, joining several European central banks in raising rates. As governments in the developed world face a mix of fiscal deficits and stubborn inflation, longer-dated sovereign bond yields are climbing as well.
Against this backdrop, we believe it is particularly important to distinguish between businesses whose financial outcomes are dependent on prevailing macro conditions and those capable of succeeding across a range of environments. We recognize that “quality” is an over-used term—and often used too broadly—across the investment industry. For us, it is important to distinguish among three distinct forms of quality:
- Transient Quality can look exceptional at the peak of a cycle, with scarcity-driven pricing power, expanding margins and high returns on capital. On the surface the economics can appear highly attractive, but when supply eventually catches up, prices normalize and investors realize what has happened, significant valuation resets can occur.
- Conventional Quality possesses many of the characteristics traditionally associated with great businesses—powerful brands, customer loyalty, incumbency advantages and ecosystem lock-in—but the old moats are eroding. Digital advertising, ecommerce, private label, low barriers to entry and technological disruption have made certain franchises less structurally resilient than they once were.
- Durable Quality is where we are most energized because scarcity is permanent rather than cyclical (or at least less so). These businesses can raise prices ahead of inflation for years without impairing volume, protected by natural monopolies, geology, irreplaceable infrastructure, essentiality, regulation or deliberate scarcity. Consider businesses like luxury goods manufacturers, regulated utilities and mission-critical technology solutions, or specialty data providers, unique ingredient producers and transportation platforms.
By focusing on durable, high-quality businesses, we seek to look past short-term macroeconomic volatility and capitalize on the disconnects it can create between share prices and long-term earnings power. Importantly, we believe today’s environment continues to provide such opportunities, enabling us to selectively enhance the portfolio when we identify businesses offering a particularly compelling combination of quality, valuation and catalysts.
Performance and Attribution Summary
For the third quarter of 2026, Aristotle Capital’s Global Equity WM Composite posted a total return of 0.29% pure gross of fees (-0.20% net of fees), underperforming the MSCI ACWI Index, which returned 1.60%, and the MSCI World Index, which returned 1.88%. Please refer to the table below for detailed performance.
| Performance (%) | 3Q26 | YTD | 1 Year | 3 Years | 5 Years | 10 Years | Since Inception* |
|---|---|---|---|---|---|---|---|
| Global Equity WM Composite (pure gross) | 0.29 | 4.30 | 8.34 | 13.67 | 7.03 | 10.76 | 10.22 |
| Global Equity WM Composite (net) | -0.20 | 2.76 | 6.22 | 11.46 | 4.92 | 8.56 | 8.04 |
| MSCI ACWI Index (net) | 1.60 | 13.03 | 16.75 | 21.73 | 11.57 | 12.38 | 10.61 |
| MSCI World Index (net) | 1.88 | 11.75 | 15.24 | 21.40 | 11.89 | 12.81 | 11.31 |
Source: FactSet
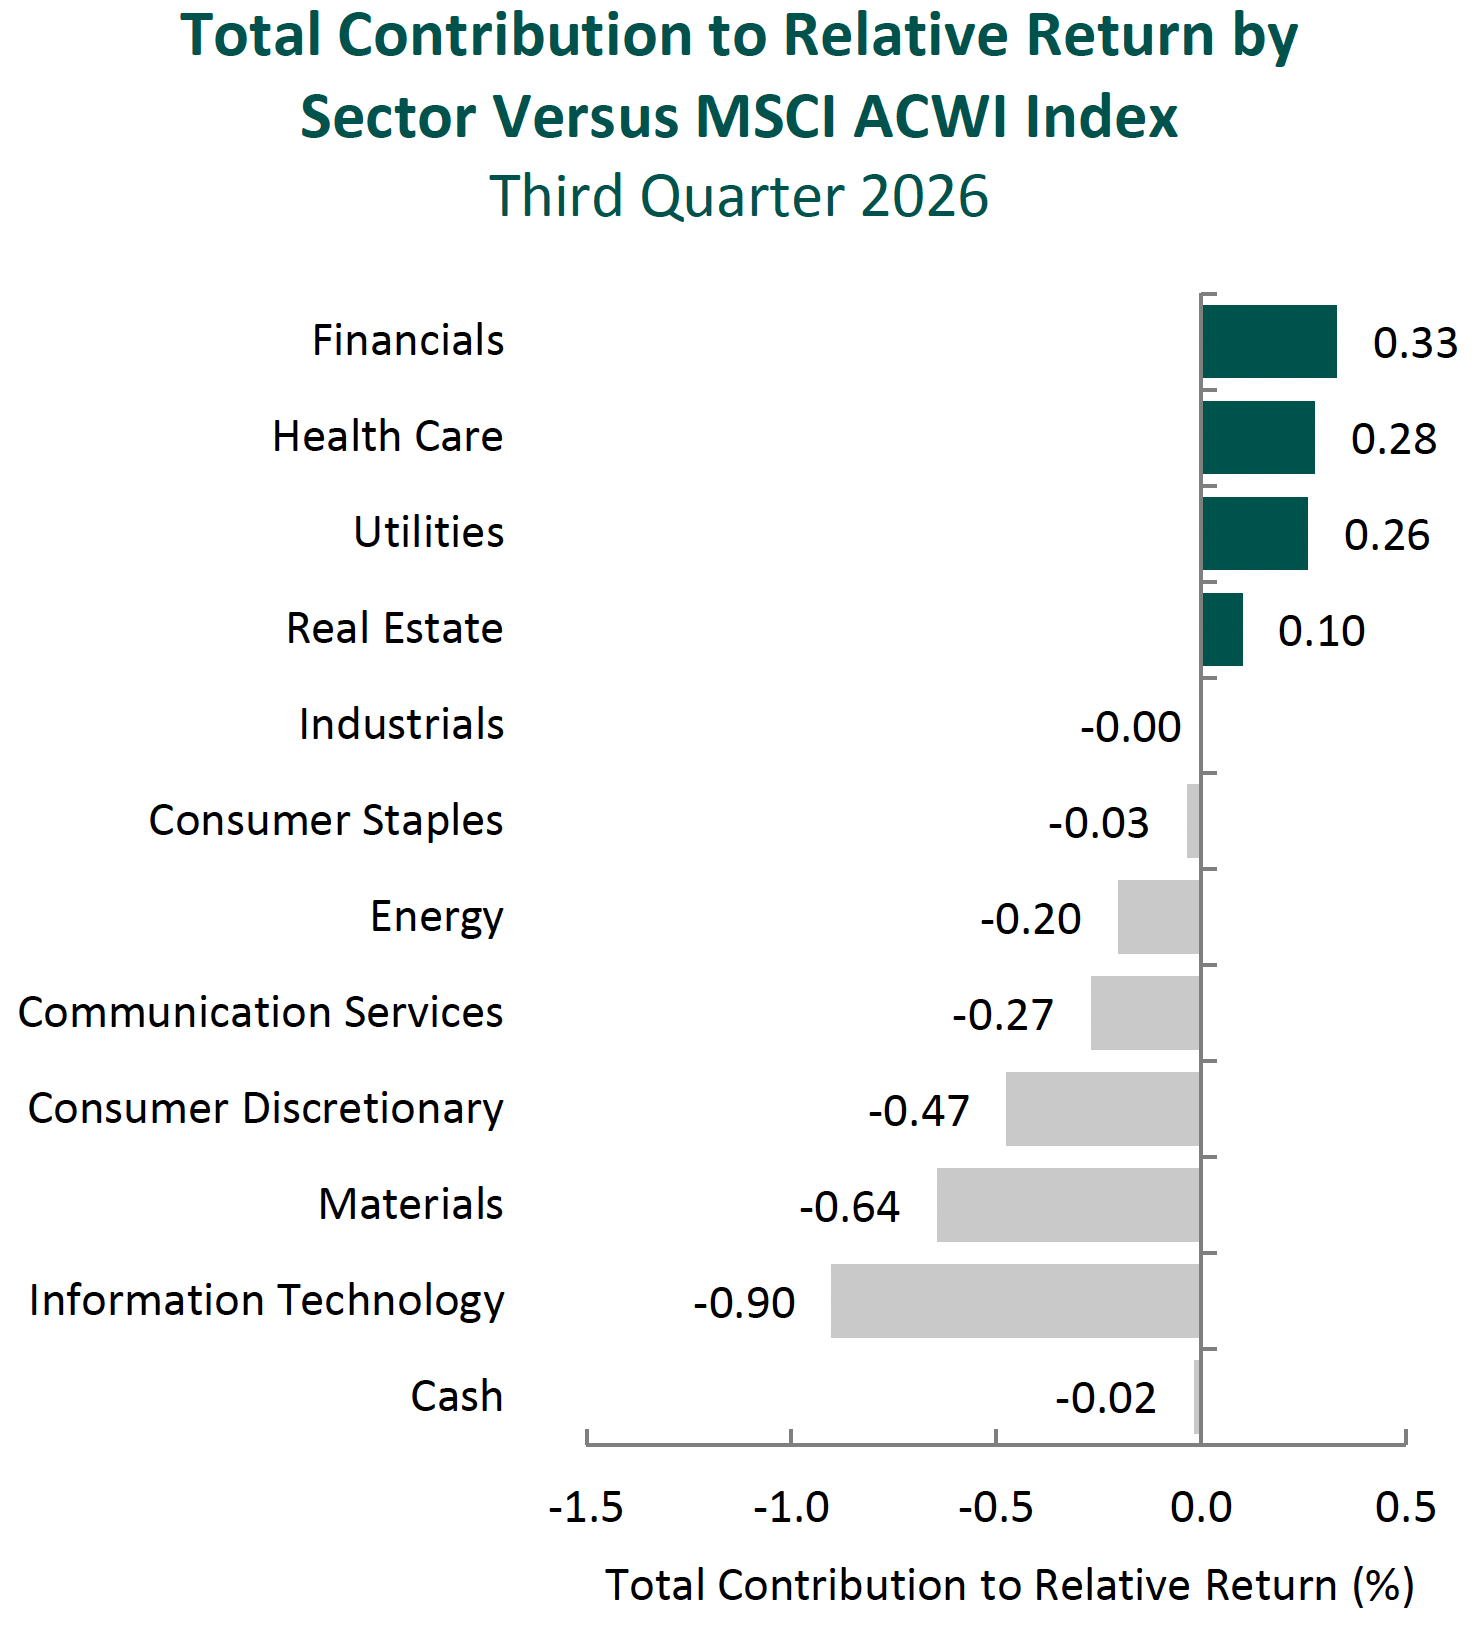
Past performance is not indicative of future results. Sector attribution shows how much of a portfolio’s overall return is directly attributable to stock selection and asset allocation decisions within the portfolio, highlighting which sectors contributed or detracted to the total return. Attribution includes the reinvestment of income. Attribution is presented pure gross of fees and does not include the deduction of all fees and expenses that a client or investor has paid or would have paid. Please refer to the gross and net composite returns included within to understand the overall impact of fees.
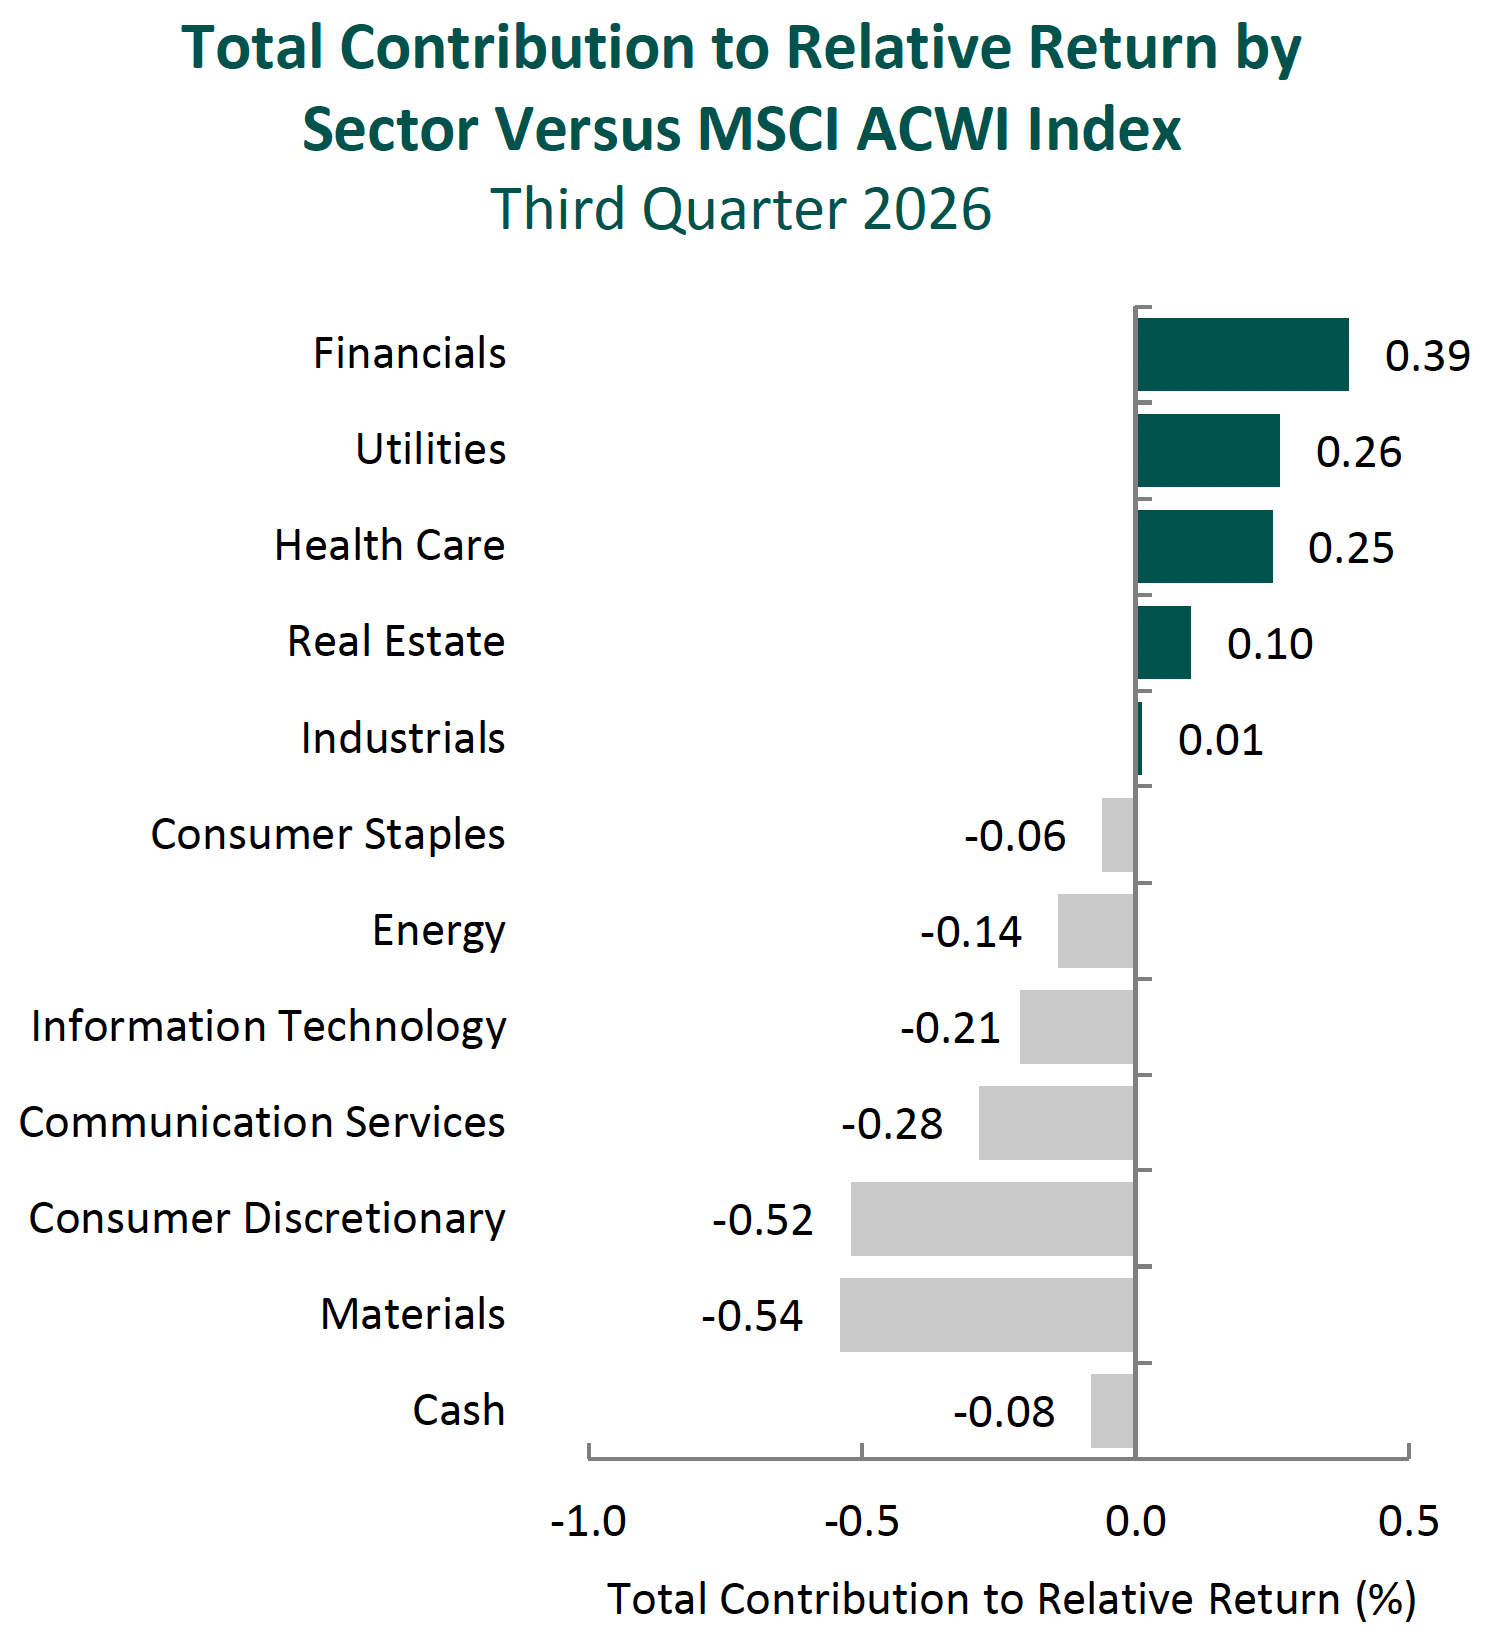
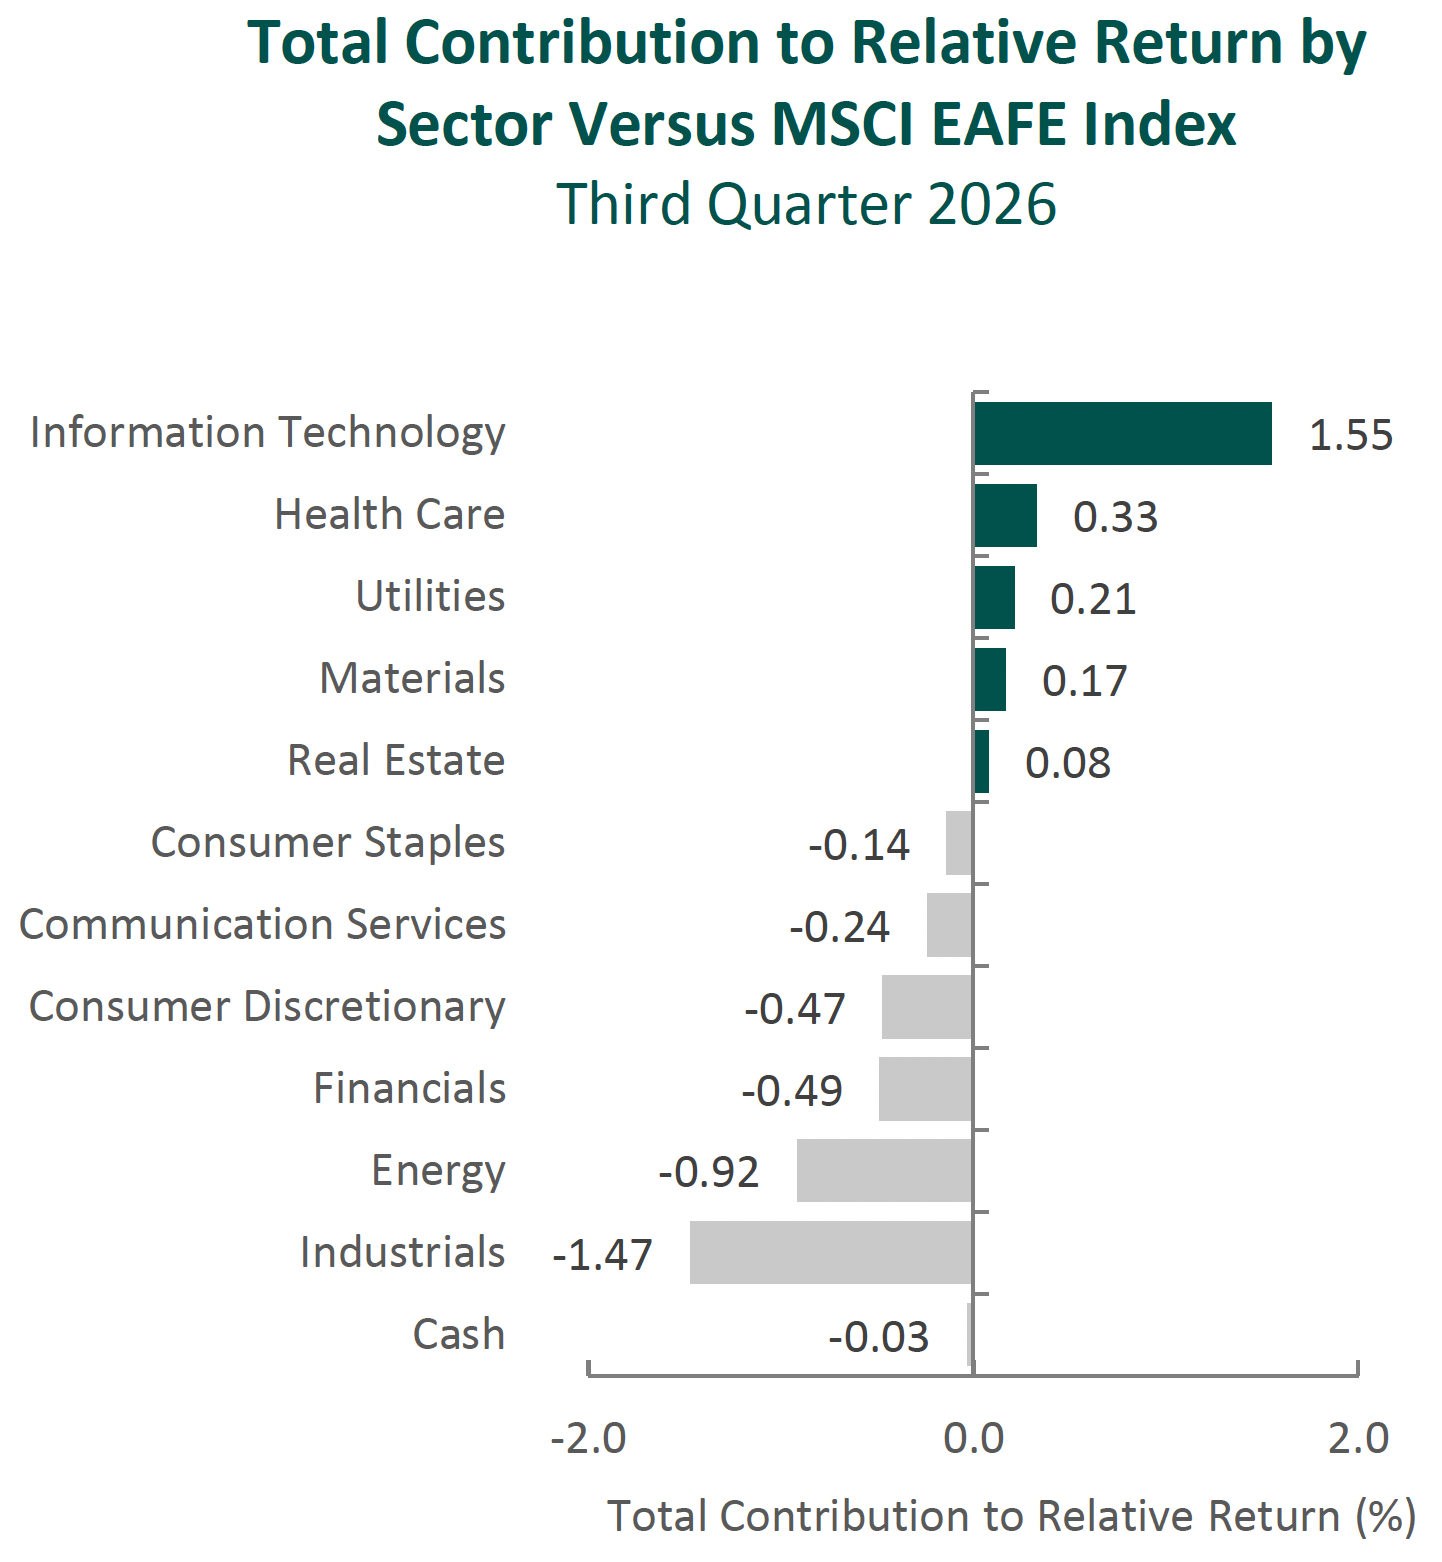
From a sector perspective, the portfolio’s underperformance relative to the MSCI ACWI Index can be attributed to both security selection and allocation effects. Security selection in Materials, Information Technology and Consumer Discretionary detracted the most from the portfolio’s relative performance. Conversely, security selection in Industrials and Financials, as well as a lack of exposure to Utilities, contributed most to relative return.
Regionally, security selection was responsible for the portfolio’s underperformance relative to the MSCI ACWI Index while allocation effects contributed. Security selection in North America detracted the most from relative performance, while an overweight in Japan contributed the most.
Contributors and Detractors for 3Q 2026
| Relative Contributors | Relative Detractors |
|---|---|
| DBS Group | Martin Marietta Materials |
| ITOCHU | Microchip Technology |
| Amgen | Brookfield |
| Sony | Rentokil Initial |
| Mitsubishi UFJ Financial | Norwegian Cruise Line Holdings |
Relative contributors and detractors are based on attribution total effect and exclude benchmark securities not held in the portfolio.
Microchip Technology, the microcontroller (MCU) and analog semiconductor producer, was a detractor during the period. The company’s stock sold off despite continued evidence of improvement in its underlying business. Customer inventories continued to normalize and bookings remained strong, supporting a recovery in demand following the prolonged industry downturn. Higher factory utilization and disciplined expense management also contributed to improved profitability and cash flow generation. While management noted potential capacity constraints at certain external manufacturing partners, Microchip’s internal capacity remains sufficient to support its growth expectations. We believe the company’s broad product portfolio, long-standing customer relationships and commitment to extended product lifecycles position it well to benefit from a continued recovery in its core end markets, while growing opportunities in data centers and aerospace & defense provide additional avenues for long-term growth.
Rentokil Initial, the U.K.-based pest control and hygiene services company, was a significant detractor during the quarter. Shares declined following the company’s interim results as investors focused on weaker growth in portions of its North American pest control business and management’s decision to retire its previous 2027 North American margin target. Importantly, North American organic growth improved from the prior year, while customer retention and profitability also increased. Under newly appointed CEO Mike Duffy, the company has strengthened its North American leadership team and is undertaking a broader operational restructuring, with plans to reinvest cost savings into initiatives intended to accelerate organic growth rather than maximize near-term margins. While we continue to assess the new management team’s strategy and execution, we believe Rentokil’s scale, route density and recurring service model provide the company with meaningful competitive advantages.
DBS Group, a leading Asian financial services company headquartered in Singapore, was the top contributor during the quarter. Shares rose following another strong earnings report, with record earnings supported by continued growth in wealth management and other fee-based businesses, as well as resilient net interest income despite lower local interest rates. The company continues to benefit from growing wealth creation across Asia, while its strong capital position has supported increased shareholder distributions and disciplined capital allocation. We believe DBS’s strong market position, diversified sources of earnings and disciplined capital allocation support attractive long-term returns.
Amgen, the biopharmaceutical company, was one of the largest contributors during the quarter. The company has continued to benefit from growth across several newer and expanding medicines, including Repatha (cholesterol), Evenity (osteoporosis), Tezspire (asthma) and Uplizna (rare autoimmune diseases), while also emphasizing clinical developments across its pipeline. While Amgen faces increasing biosimilar competition for several of its mature biologic therapies, the company is also benefiting from opportunities in the growing biosimilars market. Leveraging its biologics expertise and global manufacturing scale, the company has generated more than $15 billion in biosimilar sales since 2018, with additional candidates in development. We believe the breadth of Amgen’s portfolio and improving research productivity, combined with its ability to capitalize on its global commercial and manufacturing infrastructure, position the company to benefit as its pipeline develops.
Recent Portfolio Activity
| Buys | Sells |
|---|---|
| E Ink Holdings* | Assa Abloy* |
| McKesson | Oshkosh |
During the quarter, we sold our positions in Assa Abloy and Oshkosh and purchased E Ink Holdings and McKesson.
We first purchased Assa Abloy, the world’s largest provider of door opening and entrance solutions, in 2016. Over our investment period, the company strengthened its leading position in a fragmented industry, benefiting from significant replacement and upgrade demand, as well as the growing adoption of higher-value electromechanical and digital access solutions. The company also continued to build on its long track record of acquiring businesses and creating additional value through integration, operational improvement and access to its global platform. More recently, however, we believe the opportunity for incremental value creation through M&A has become less compelling, while opportunities to further optimize the company’s existing portfolio appear unlikely. As such, we chose to exit our position and redeploy capital into opportunities we believe offer a more attractive combination of valuation and catalysts. (*E Ink does not offer an ADR or GDR and was purchased only in accounts registered to trade on the Taiwan Stock Exchange. For those accounts unable to purchase E Ink, Assa Abloy continues to be held as a replacement.)
We first invested in Oshkosh, a manufacturer of specialty vehicles and access equipment, in the third quarter of 2013. During our holding period, we believe the company executed well on many of the catalysts we had identified, including improved profitability through pricing discipline, manufacturing efficiencies, a more favorable business mix, continued product innovation and the ramp-up of production of the U.S. Postal Service’s Next Generation Delivery Vehicle program. Given the progress, we chose to sell our position and redeploy the proceeds into what we believe is a more attractive opportunity in McKesson.
E Ink Holdings Inc.
Headquartered in Hsinchu, Taiwan, E Ink is the global leader in electronic paper (“ePaper”) display technology. Unlike traditional LCD or OLED screens, ePaper uses electrically charged color pigments to create a paper-like display that reflects ambient light and only requires power when an image changes. These characteristics allow ePaper displays to remain visible for extended periods while consuming very little energy, making the technology particularly well-suited for applications such as eReaders, electronic shelf labels (“ESLs”), eNotes and digital signage. E Ink holds an estimated 80%-90% share of the global ePaper display market and is currently the only manufacturer capable of mass-producing high-quality ePaper technology at scale.
Historically, E Ink was best known for supplying the displays used in eReaders such as Amazon’s Kindle and Rakuten’s Kobo. However, the business is increasingly being driven by ESLs—digital price tags that allow retailers to remotely update prices, promotions and product information across stores in real time. ESLs can reduce the labor associated with manually replacing paper labels, improve pricing accuracy and increasingly support inventory management and order fulfillment. E Ink does not manufacture the finished labels; rather, it supplies its proprietary ePaper material to leading ESL manufacturers, allowing the company to participate broadly in the growth of the market without competing in the more commoditized assembly business.
High-Quality Business
Some of the quality characteristics we have identified for E Ink include:
- A dominant position in ePaper displays, supported by proprietary technology, extensive intellectual property and decades of research and development;
- Significant barriers to entry arising from the technical complexity of ePaper manufacturing and the need for consistent product quality, scale and established relationships with leading device manufacturers and ESL solution providers; and
- A strong financial profile, including a net cash balance sheet and attractive returns on capital.
Attractive Valuation
We believe shares trade at a meaningful discount to our estimate of intrinsic value based on E Ink’s normalized earnings potential. Our analysis reflects the company’s long runway for growth across ePaper applications while recognizing the established earnings contribution from eReaders and eNotes.
Compelling Catalysts
Catalysts we have identified for E Ink, which we believe will cause its stock price to appreciate over our three- to five-year investment horizon, include:
- Continued adoption of ESL, particularly in the underpenetrated U.S. market, as retailers automate price changes, to reduce manual labor requirements and better integrate physical stores with inventory and order-management systems;
- Improving business mix as higher-margin ESL and other IoT applications become a larger portion of revenue, supporting higher normalized margins and returns over time;
- Growing replacement and upgrade demand as earlier ESL installations are refreshed with newer generations of the technology; and
- Expansion of ePaper into digital signage, supported by growing adoption of E Ink’s color technologies across retail, advertising and other commercial applications.
McKesson Corporation
Headquartered in Irving, Texas, and founded in 1833, McKesson is the market leader in U.S. pharmaceutical distribution. The company serves as a critical intermediary within the healthcare system, sourcing branded, generic, specialty, biosimilar and over-the-counter pharmaceuticals from manufacturers and delivering them to retail pharmacies, hospitals, health systems, physician practices, long-term care providers and other healthcare customers. Together with Cardinal Health and Cencora, McKesson is one of three dominant national pharmaceutical distributors that collectively account for more than 90% of the U.S. market.
McKesson’s role extends well beyond the physical distribution of pharmaceuticals. The company manages sourcing and inventory to help ensure reliable product availability, provides technology solutions, and helps manufacturers efficiently reach thousands of healthcare providers through a scaled distribution network. Over time, the company has expanded further into higher-value healthcare services, including oncology and multispecialty practice solutions, biopharma services, and prescription technology solutions that help improve medication access, affordability and adherence.
High-Quality Business
Some of the quality characteristics we have identified for McKesson include:
- Mission-critical distribution capabilities that are difficult to replicate, supported by national scale, extensive infrastructure and regulatory expertise;
- Long-standing customer relationships and multi-year distribution agreements that create meaningful switching costs and deepen McKesson’s role within the U.S. healthcare system;
- Attractive underlying economics, including what we consider to be strong returns on invested capital and FREE cash flow generation, supported by limited capital requirements and favorable working-capital dynamics; and
- Resilient demand characteristics, as prescription drug utilization is largely non-discretionary and less sensitive to broader macroeconomic cycles.
Attractive Valuation
We believe shares of McKesson are attractively valued given our estimates of normalized earnings. In our view, the company’s low reported distribution margins understate the attractive economics of its core pharmaceutical distribution business, while its growing higher-margin businesses in Oncology & Multispecialty, biopharma services and Prescription Technology Solutions should support higher normalized earnings and FREE cash flow over time.
Compelling Catalysts
Catalysts we have identified for McKesson, which we believe will cause its stock price to appreciate over our three- to five-year investment horizon, include:
- Continued expansion of the Oncology & Multispecialty segment through additional physician practices and a growing suite of services spanning drug distribution, technology, clinical research and practice management;
- Continued growth in biopharma services and Prescription Technology Solutions, as McKesson helps manufacturers, providers, pharmacies and patients improve medication access, affordability and adherence;
- Expansion of McKesson’s oncology practice-management capabilities into adjacent specialties, such as ophthalmology, through targeted acquisitions and internal investment;
- Ongoing expansion of NorthStar Rx (McKesson’s own private-label generic pharmaceutical business) into biosimilars, leveraging its established oncology relationships as biosimilar adoption grows; and
- Ongoing progress toward the separation of Medical-Surgical Solutions, allowing management to focus capital and resources on McKesson’s higher-return businesses.
Conclusion
Periods of relative underperformance can test conviction, particularly when market leadership is narrow and rapidly changing. However, we believe the appropriate response is not to chase what has recently worked but to remain focused on the long-term drivers of value creation. This discipline has guided our investment process across multiple market cycles and continues to shape how we position the portfolio today.
Importantly, recent performance has not been accompanied by a deterioration in the businesses we own. In many cases, earnings have continued to grow even as valuation multiples have compressed, creating what we believe is an increasingly attractive disconnect between share prices and normalized earnings power. While periods like this are challenging, they can also create opportunity for long-term investors. We believe the very conditions that have challenged recent relative performance have strengthened the portfolio’s prospective return potential.
The opinions expressed herein are those of Aristotle Capital Management, LLC (Aristotle Capital) and are subject to change without notice. Past performance is not a guarantee or indicator of future results. This material is not financial advice or an offer to buy or sell any product. You should not assume that any of the securities transactions, sectors or holdings discussed in this report were or will be profitable, or that recommendations Aristotle Capital makes in the future will be profitable or equal the performance of the securities listed in this report. The portfolio characteristics shown relate to the Aristotle Global Equity Advisory strategy. Not every client’s account will have these characteristics. Aristotle Capital reserves the right to modify its current investment strategies and techniques based on changing market dynamics or client needs. There is no assurance that any securities discussed herein will remain in an account’s portfolio at the time you receive this report or that securities sold have not been repurchased. The securities discussed may not represent an account’s entire portfolio and, in the aggregate, may represent only a small percentage of an account’s portfolio holdings. The performance attribution presented is of a representative account from Aristotle Capital’s Global Equity WM Composite. The representative account is a discretionary client account which was chosen to most closely reflect the investment style of the strategy. The criteria used for representative account selection is based on the account’s period of time under management and its similarity of holdings in relation to the strategy. Recommendations made in the last 12 months are available upon request.
Composite returns are presented pure gross and net of the maximum wrap fee and include the reinvestment of all income. Pure gross returns do not reflect the deduction of any trading costs or other fees and are supplemental to the net returns. Net returns are calculated by subtracting the highest applicable wrap/SMA fee, which includes trading costs and custodial fees, from the pure gross composite return. The highest applicable wrap/SMA fee is 2.00% on an annual basis, or 0.50% quarterly from inception to 12/31/2023 and 0.17% monthly from 1/1/2024 to present.
All investments carry a certain degree of risk, including the possible loss of principal. Investments are also subject to political, market, currency and regulatory risks or economic developments. International investments involve special risks that may in particular cause a loss in principal, including currency fluctuation, lower liquidity, different accounting methods and economic and political systems, and higher transaction costs. These risks typically are greater in emerging markets. While Large-capitalization companies may have more stable prices than smaller, less established companies, they are still subject to equity securities risk. In addition, large-capitalization equity security prices may not rise as much as prices of equity securities of small-capitalization companies. Securities of small- and medium-sized companies tend to have a shorter history of operations and be more volatile and less liquid. Value stocks can perform differently from the market as a whole and other types of stocks. The material is provided for informational and/or educational purposes only and is not intended to be and should not be construed as investment, legal or tax advice and/or a legal opinion. Investors should consult their financial and tax adviser before making investments. The opinions referenced are as of the date of publication, may be modified due to changes in the market or economic conditions, and may not necessarily come to pass. Information and data presented has been developed internally and/or obtained from sources believed to be reliable. Aristotle Capital does not guarantee the accuracy, adequacy or completeness of such information.
Aristotle Capital Management, LLC is an independent investment adviser registered under the Investment Advisers Act of 1940, as amended. Registration does not imply a certain level of skill or training. More information about Aristotle Capital, including our investment strategies, fees and objectives, can be found in our Form ADV Part 2, which is available upon request. ACM-2610-126
Sources: CAPS CompositeHubTM, MSCI
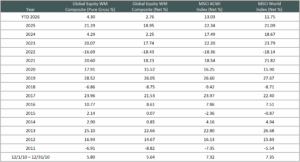
The Aristotle Global Equity WM Composite has an inception date of December 1, 2010. As of 1/1/2024, the composite was renamed from the Global Equity Advisory Composite.
Past performance is not indicative of future results. The information provided should not be considered financial advice or a recommendation to purchase or sell any particular security or product. Performance results for periods greater than one year have been annualized.
Composite returns are presented pure gross and net of the maximum wrap fee and include the reinvestment of all income. Pure gross returns do not reflect the deduction of any trading costs or other fees and are supplemental to the net returns. Net returns are calculated by subtracting the highest applicable wrap/SMA fee, which includes trading costs and custodial fees, from the pure gross composite return. The highest applicable wrap/SMA fee is 2.00% on an annual basis, or 0.50% quarterly from inception to 12/31/2023 and 0.17% monthly from 1/1/2024 to present.
The MSCI ACWI Index captures large and mid cap representation across Developed Markets (DM) and Emerging Markets (EM) countries. The index covers approximately 85% of the global investable equity opportunity set. The MSCI ACWI Equal Weighted Index represents an alternative weighting scheme to its market capitalization-weighted parent index, the MSCI ACWI. The Index includes the same constituents as its parent. However, at each quarterly rebalance date, all index constituents are weighted equally, effectively removing the influence of each constituent’s current price (high or low). The MSCI World Index captures large and mid cap representation across Developed Markets (DM) countries. The index covers approximately 85% of the free float-adjusted market capitalization in each country. The MSCI Emerging Markets Index captures large and mid cap representation across Emerging Markets (EM) countries. The index covers approximately 85% of the free float-adjusted market capitalization in each country. The MSCI ACWI Growth Index captures large and mid cap securities exhibiting overall growth style characteristics across Developed Markets (DM) and Emerging Markets (EM) countries. The MSCI ACWI Value Index captures large and mid cap securities exhibiting overall value style characteristics across Developed Markets (DM) and Emerging Markets (EM) countries. The MSCI Europe Index captures large and mid cap representation across Developed Markets (DM) countries in Europe. The Index covers approximately 85% of the free float-adjusted market capitalization across the European Developed Markets equity universe. The MSCI Japan Index is designed to measure the performance of the large and mid cap segments of the Japanese market. The Index covers approximately 85% of the free float-adjusted market capitalization in Japan. The S&P 500® Index is the Standard & Poor’s Composite Index and is a widely recognized, unmanaged index of common stock prices. It is market cap weighted and includes 500 leading companies, capturing approximately 80% coverage of available market capitalization. The S&P 500® Equal Weight Index is designed to be the size-neutral version of the S&P 500. It includes the same constituents as the market capitalization-weighted S&P 500, but each company in the S&P 500 Equal Weight Index is allocated the same weight at each quarterly rebalance. The Bloomberg Global Aggregate Bond Index is a flagship measure of global investment grade debt from 27 local currency markets. This multi-currency benchmark includes treasury, government-related, corporate and securitized fixed-rate bonds from both developed and emerging markets issuers. The Brent Crude Oil Index is a major trading classification of sweet light crude oil that serves as a major benchmark price for purchases of oil worldwide. The volatility (beta) of the Composite may be greater or less than the benchmarks. It is not possible to invest directly in these indexes.