ARISTOTLE CAPITAL BOSTON, LLC

Markets Review

U.S. small/mid cap equities delivered robust performance in the third quarter of 2025, with the Russell 2500 Index reaching its first all-time high since November 2024. The rally was driven by a generally favorable macroeconomic backdrop, including a 25 basis point rate cut by the Federal Reserve in September, which marked a shift toward more accommodative policy amid signs of labor market softening. U.S. GDP growth remained strong at 3.8% in Q2, supported by resilient consumer spending and the easing of trade tensions following tariff rollbacks. Inflation edged higher to 2.9%, driven in part by energy costs and tariff passthroughs, but remained within a manageable range for businesses and consumers. Sentiment was risk-on, fueled by Artificial Intelligence driven optimism as companies with AI exposure or disruptive potential saw disproportionate gains, as investors chased momentum and future earnings potential over traditional valuation metrics. Small/mid-caps benefited from dovish Fed rhetoric, attractive relative valuations, broadening of market breadth, earnings recovery and a rotation away from mega cap stocks.

Stylistically, growth stocks outperformed their value counterparts during the quarter as the Russell 2500 Growth Index returned 10.73% compared to the 8.17% return of the Russell 2500 Value index. This continues the 2024 trend where growth significantly outperformed value.

From a factor perspective, lower quality companies significantly outperformed higher quality companies during the quarter. Factors that had the strongest payoffs were high beta, momentum, higher volatility, non-earners, high sales growth, micro caps, cyclical, and highly shorted stocks.

The best performing sectors were Information Technology (+14.47%), Health Care (+12.37%), and Utilities (+12.30%), while the worst performing sectors were Consumer Staples (-3.77%), Financials (+4.02%), and Real Estate (+5.79%).
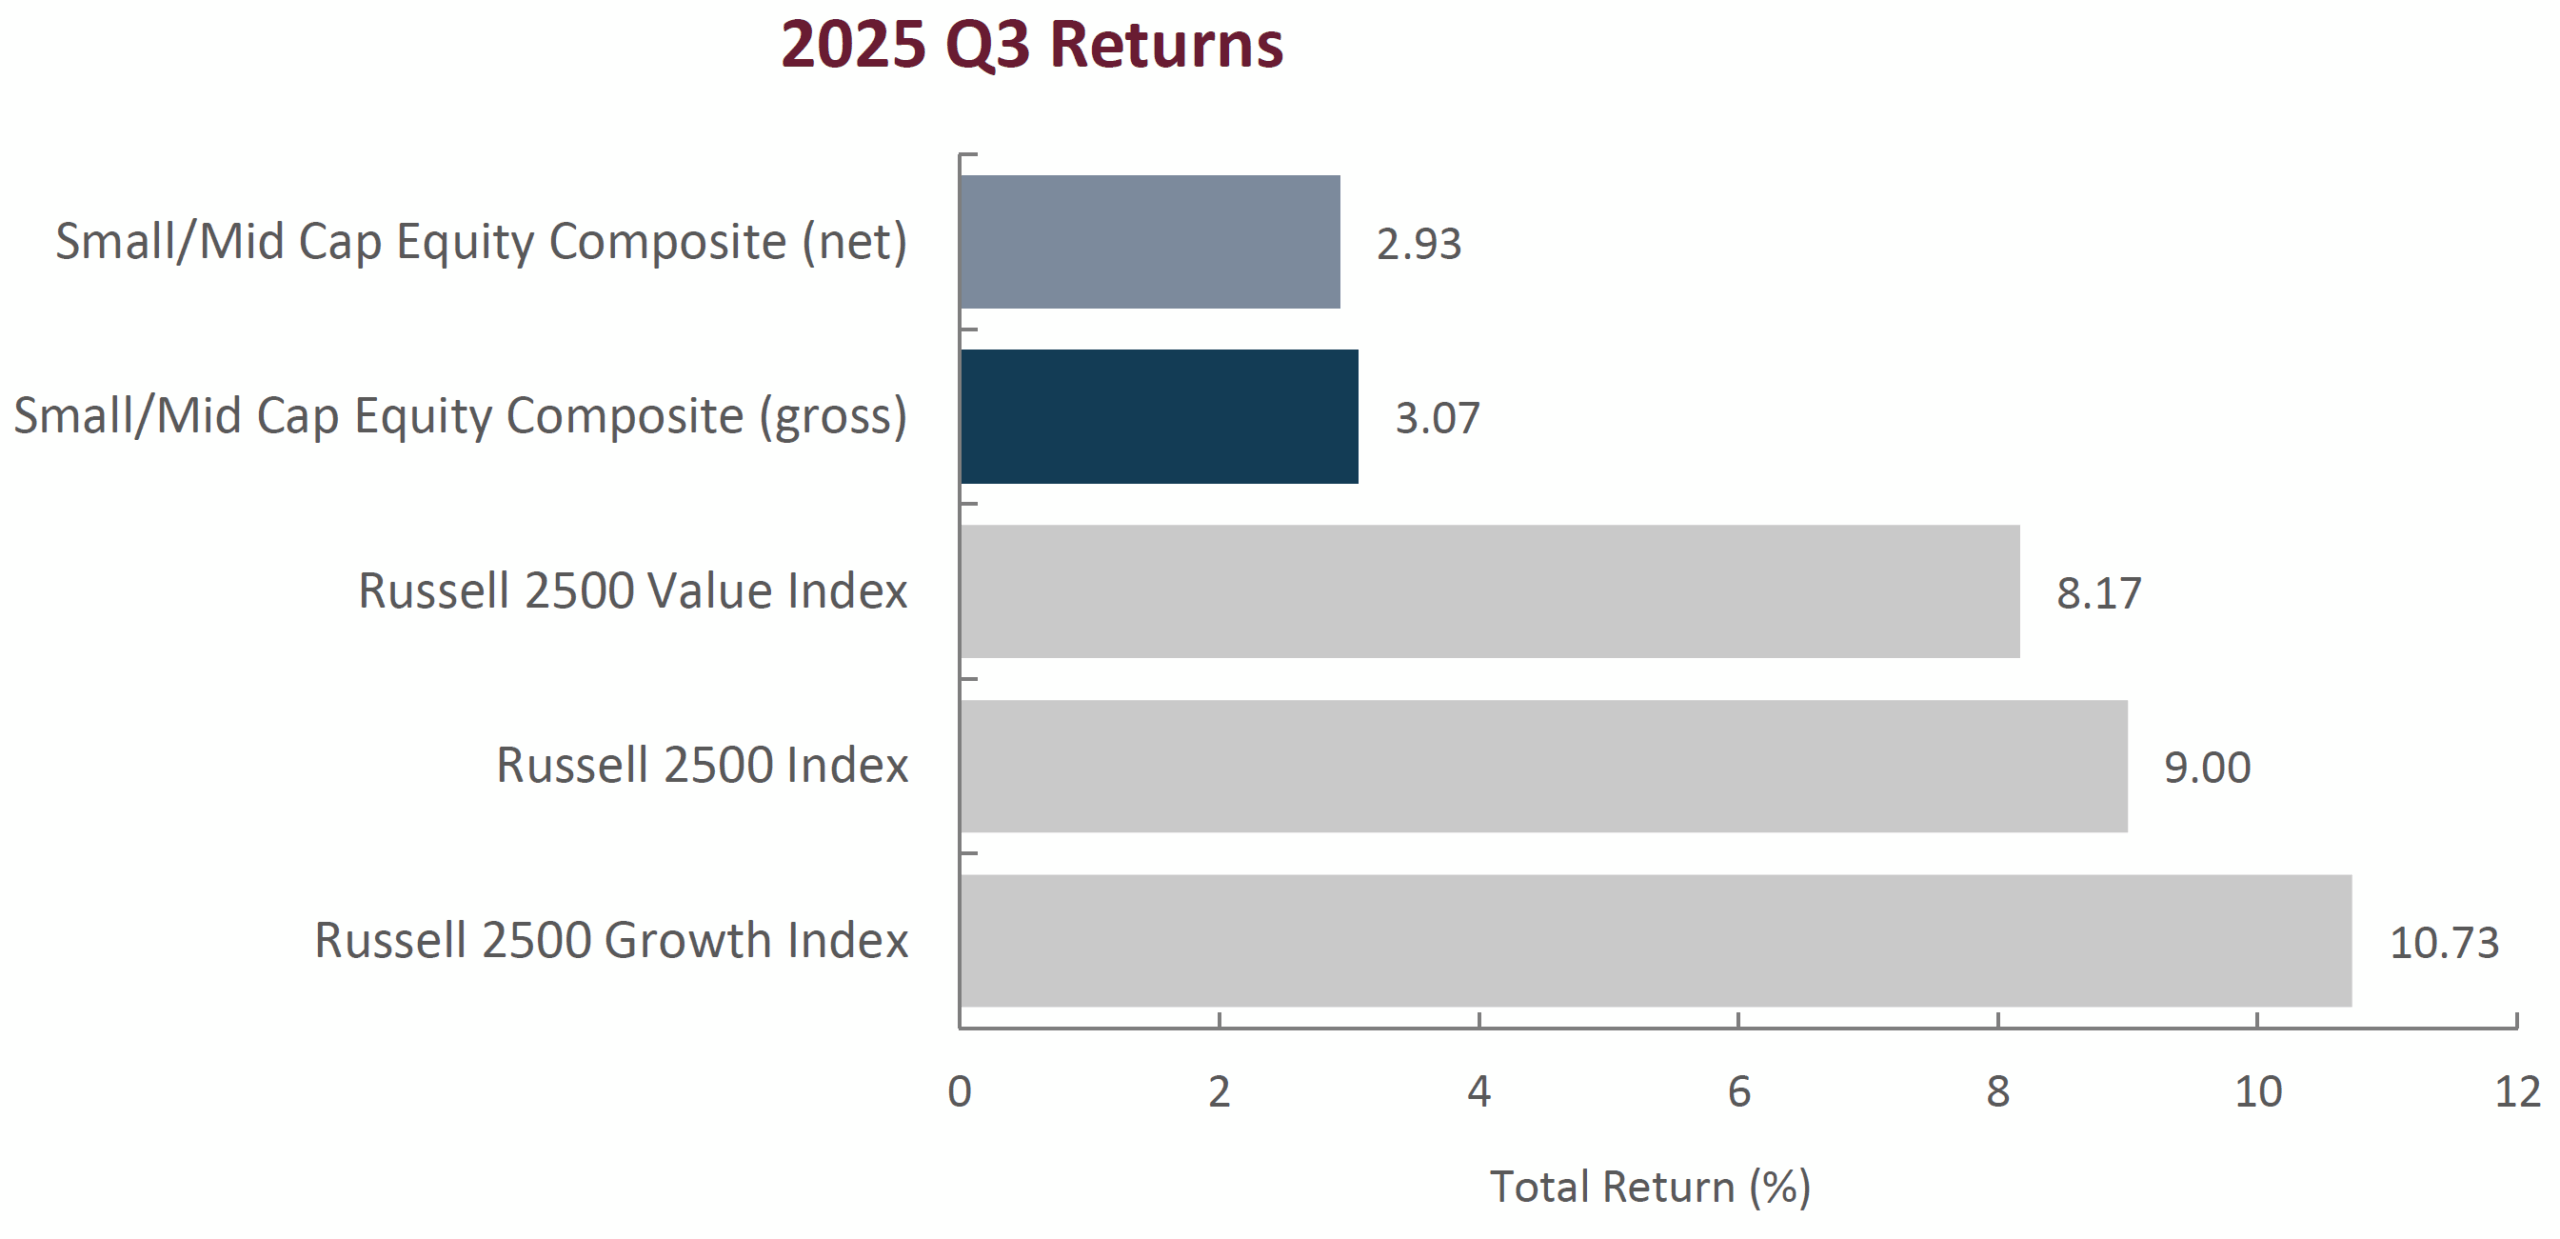
Sources: CAPS Composite Hub, Russell Investments

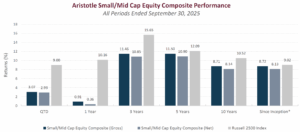
Sources: CAPS Composite Hub, Russell InvestmentsPast performance is not indicative of future results. Returns are presented gross and net of investment advisory fees and include the reinvestment of all income. Gross returns will be reduced by fees and other expenses that may be incurred in the management of the account. Net returns are presented net of actual investment advisory fees and after the deduction of all trading expenses. Aristotle Small/Mid Cap Equity Composite returns are preliminary pending final account reconciliation. Please see important disclosures at the end of this document.

Performance Review

For the third quarter of 2025, the Aristotle Small/Mid Cap Equity Composite generated a total return of 2.93% net of fees (3.07% gross of fees), underperforming the 9.00% total return of the Russell 2500 Index. The largest detractor from relative performance was security selection in Health Care (a combination of stocks we owned coupled with not owning biotechnology), Industrials and Materials. This was partially offset by strong security selection in Consumer Discretionary coupled with an overweight allocation to Information Technology and an underweight allocation to Financials.

Relative ContributorsRelative Detractors
CienaHaemonetics
Alamos GoldMACOM Technology Solutions
Supernus PharmaceuticalsGartner
Wolverine World WideBaldwin Insurance Group
Advanced Energy Industries James Hardie Industries

CONTRIBUTORS

Ciena (CIEN), is an optical networking equipment manufacturer for telecommunications and web scale network operators. The stock was bolstered due to strong earnings results and optimistic forward guidance driven by AI-related demand and technological innovation. We believe the company is well-positioned to benefit from strong demand for bandwidth given its differentiated product portfolio and history of technological innovation, which should lead to strong operating results and shareholder value creation.

Alamos Gold (AGI-CA), engages in the exploration, development, mining and extraction of precious metals. The company benefited from rising gold prices as investors purchased the commodity as an inflation hedge. We maintain our investment as we believe in the company’s lower geopolitical risk profile, solid production growth plan from 600k oz to 1M oz per year over the next five years, and strong operational track record.

DETRACTORS

Haemonetics (HAE), is a global provider of hematology and blood management products and solutions. The company delivered mixed results during the quarter, beating analyst earnings estimates but posting weaker than expected revenue results. We believe that the company’s strong competitive position within the plasmapheresis market along with increased investment in research and development should create value for shareholders over a multi-year period.

MACOM Technology Solutions (MTSI), is a designer and manufacturer of high-performance semiconductor products. Despite reporting strong Q3 earnings, the stock declined as investors reacted to a slight margin impact from a recent acquisition and a slower-than-expected recovery in the industrial market—both short-term deviations from analyst forecasts. We maintain our position, as we believe the company’s meaningful exposure to growing demand from Data Center and 5G end market applications along with the integration of recent acquisitions and domestic manufacturing footprint should drive additional shareholder value in periods to come.

Recent Portfolio Activity

Buys/AcquisitionsSells/Liquidations
Columbia Banking Systems 1-800-FLOWERS.COM
Essential Utilities ALLETE
Hilton Grand VacationsAZEK
James Hardie IndustriesCarter’s
Pinnacle West CapitalPacific Premier Bancorp
Primo Brands NCR Voyix
Service Corporation International

BUYS/ACQUISITIONS

Columbia Banking System (COLB), is a Washington state based commercial bank that is in the early stages of winding down a large portfolio of low-yielding loans with organically driven higher yielding relationship loans and lower cost core deposit funding. A combination of operational cost savings associated with the Pacific Premier Bancorp merger and an increased focus on increasing fee-based income should allow for higher than historical profit margins and an attractive EPS growth outlook, ultimately allowing for incremental share buybacks or dividend increases.

Essential Utilities (WTRG), is a Pennsylvania-based utility providing water, wastewater, and natural gas services across nine states through its Aqua and Peoples Gas subsidiaries. Rate base expansion should continue to be driven by ongoing infrastructure investments and municipal water system acquisitions. A favorable regulatory landscape in the company’s core markets, including Pennsylvania and Texas, supports operational stability and consistent dividend growth. The company is a designated “Dividend Aristocrat”, having raised its dividend for 34 straight years.

Hilton Grand Vacations (HGV), is a leading global timeshare company that develops, markets and operates a system of brand-name, high-quality vacation ownership resorts in select vacation destinations, under the brand names: Hilton Vacation Club, Hilton Grand Vacation Club, Hilton Club. HGV’s proprietary relationship with Hilton Worldwide Holdings (HLT) allows it to market exclusively to HLT’s 180 mil Hilton Honors members to capitalize on growing demand for travel. Recent acquisitions broadened the company resort base to include properties appealing to higher income consumers.

James Hardie Industries (JHX), manufactures Fiber Cement and Fiber Gypsum products (siding, backerboard, etc.) used primarily in residential construction (newbuild and repair/remodel). JHX acquired the existing portfolio company, The AZEK Company (AZEK), which provides JHX with a broader product offering for distributors, contractors and homeowners, positioning the company for market share gains in an expanded addressable market. Operating synergies, merger cost synergies and enhanced scale efficiencies should further enhance the shareholder value creation potential.

Pinnacle West Capital (PNW), is an Arizona-based, vertically integrated electric utility company serving central Arizona. Population migration and the expansion of industrial manufacturing within the Phoenix metropolitan area is driving increased energy demand and capital investment opportunities for the company. An improving regulatory backdrop in Arizona should also allow for reduced earnings volatility and accelerated cost recovery moving forward.

Primo Brands (PRMB), is a branded beverage company focused on healthy hydration. The company is the top player in U.S. bottled water with approximately 19% market share. The portfolio of brands is well diversified across distribution channels, product format, sizes and price points that allow the company to cost efficiently reach 90% of the U.S. population. Increasing consumption of bottled water should be supported by concerns about municipal tap water quality, the wellness movement leading to lower consumption of soda, juice, and alcoholic beverages, and innovation in water flavors and premium products attracting consumers toward the category.

Service Corporation International (SCI), is North America’s largest provider of deathcare products and services. The company is strategically positioned to benefit from long-term demographic tailwinds driven by the aging Baby Boomer population. Given the high fixed-cost nature of the business, rising volumes are expected to deliver operating leverage, driving margin expansion and increased cash generation. Total shareholder value is further enhanced by a balanced capital allocation strategy, featuring dividends, share repurchases, and accretive acquisitions that strengthen the company’s market leadership.

SELLS/LIQUIDATIONS

1-800-FLOWERS.COM (FLWS), is an e-commerce provider of floral and gift products. The position was liquidated due to an increasingly uncertain fundamental outlook.

ALLETE (ALE), is a Minnesota based electric utility company. The position was liquidated ahead of its pending acquisition by a private equity consortium.

AZEK (AZEK), is a manufacturer of composite decking products for primarily residential applications. The company was acquired by James Hardie Industries plc (JHX).

Carter’s (CRI), is a manufacturer, distributor and retailer of infant and young children’s apparel. The position was liquidated due to deteriorated fundamental performance and an uncertain strategic outlook.

Pacific Premier Bancorp (PPBI), a California based bank holding company, was acquired by Columbia Banking System (COLB).

NCR Voyix (VYX), is a provider of digital commerce solutions to the retail, restaurants, and digital banking industries. The position was liquidated due to deteriorating fundamental performance following the spin out from NCR Corporation.

Outlook

We remain optimistic about the long-term potential for the small/mid-cap segment of the U.S. market. Valuations remain compelling relative to large caps, with the Russell 2500 Index trading near the lower end of its historical range. Potential tailwinds, including deregulation, lower corporate tax rates, increased M&A activity, continued reshoring of U.S. manufacturing, and infrastructure-related spending, could provide additional support for small/mid-cap stocks. Volatility remains elevated over concerns around inflationary risks, geopolitical tensions, and potential U.S. economic and labor weakness.

Positioning

Our current positioning is a function of our bottom-up security selection process and our ability to identify what we view as attractive investment candidates, regardless of economic sector definitions. Overweights in Information Technology and Materials are mostly a function of our underlying company specific views rather than any top-down predictions for each sector. Conversely, we continue to be underweight in Consumer Discretionary, as we have been unable to identify what we consider to be compelling long-term opportunities that fit our discipline given the rising risk profiles of many retail businesses and a potential deceleration in goods spending following a period of strength. We are also underweight in Financials as the sector has experienced strong returns, leading us to harvest gains and redeploy the proceeds to what we consider to be more attractive reward to risk opportunities. Given our focus on long-term business fundamentals, our patient investment approach and low portfolio turnover, the strategy’s sector positioning generally does not change significantly from quarter to quarter. However, we may take advantage of periods of volatility by adding selectively to certain companies when appropriate.

Disclosures

The opinions expressed herein are those of Aristotle Capital Boston, LLC (Aristotle Boston) and are subject to change without notice.

Past performance is not indicative of future results. The information provided in this report should not be considered financial advice or a recommendation to purchase or sell any particular security. There is no assurance that any securities discussed herein will remain in an account’s portfolio at the time you receive this report or that securities sold have not been repurchased. The securities discussed may not represent an account’s entire portfolio and, in the aggregate, may represent only a small percentage of an account’s portfolio holdings. The performance attribution presented is of a representative account from Aristotle Boston’s Small/Mid Cap Equity Composite. The representative account is a discretionary client account which was chosen to most closely reflect the investment style of the strategy. The criteria used for representative account selection is based on the account’s period of time under management and its similarity of holdings in relation to the strategy. It should not be assumed that any of the securities transactions, holdings or sectors discussed were or will be profitable, or that the investment recommendations or decisions Aristotle Boston makes in the future will be profitable or equal the performance of the securities discussed herein. Aristotle Boston reserves the right to modify its current investment strategies and techniques based on changing market dynamics or client needs. Recommendations made in the last 12 months are available upon request.

Returns are presented gross and net of investment advisory fees and include the reinvestment of all income. Gross returns will be reduced by fees and other expenses that may be incurred in the management of the account. Net returns are presented net of actual investment advisory fees and after the deduction of all trading expenses.

As of December 31, 2014, there were no non-fee-paying accounts in the Composite.

All investments carry a certain degree of risk, including the possible loss of principal. Investments are also subject to political, market, currency and regulatory risks or economic developments. International investments involve special risks that may in particular cause a loss in principal, including currency fluctuation, lower liquidity, different accounting methods and economic and political systems, and higher transaction costs. These risks typically are greater in emerging markets. While Large-capitalization companies may have more stable prices than smaller, less established companies, they are still subject to equity securities risk. In addition, large-capitalization equity security prices may not rise as much as prices of equity securities of small-capitalization companies. Securities of small- and medium-sized companies tend to have a shorter history of operations, be more volatile and less liquid. Value stocks can perform differently from the market as a whole and other types of stocks. The material is provided for informational and/or educational purposes only and is not intended to be and should not be construed as investment, legal or tax advice and/or a legal opinion. Investors should consult their financial and tax adviser before making investments. The opinions referenced are as of the date of publication, may be modified due to changes in the market or economic conditions, and may not necessarily come to pass. Information and data presented has been developed internally and/or obtained from sources believed to be reliable. Aristotle Boston does not guarantee the accuracy, adequacy or completeness of such information.

Aristotle Capital Boston, LLC is an independent investment adviser registered under the Investment Advisers Act of 1940, as amended. Registration does not imply a certain level of skill or training. More information about Aristotle Boston, including our investment strategies, fees and objectives, can be found in our Form ADV Part 2, which is available upon request. ACB-2510-18
Performance Disclosures

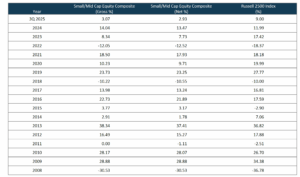
Sources: CAPS Composite Hub, Russell Investments

Composite returns for periods ended September 30, 2025, are preliminary pending final account reconciliation.

*The Aristotle Small/Mid Cap Equity Composite has an inception date of January 1, 2008, at a predecessor firm. During this time, Jack McPherson and Dave Adams had primary responsibility for managing the strategy. Performance starting January 1, 2015, was achieved at Aristotle Boston.

As of December 31, 2014, there were no non-fee-paying accounts in the Composite. Past performance is not indicative of future results. Performance results for periods greater than one year have been annualized.

Returns are presented gross and net of investment advisory fees and include the reinvestment of all income. Gross returns will be reduced by fees and other expenses that may be incurred in the management of the account. Net returns are presented net of actual investment advisory fees and after the deduction of all trading expenses. Please see important disclosures enclosed within this document.

Index Disclosures

The Russell 2500® Index measures the performance of the small to mid cap segment of the U.S. equity universe. The Russell 2500 Index is a subset of the Russell 3000® Index. It includes approximately 2500 of the smallest securities based on a combination of their market cap and current index membership. The Russell 2500 Growth® Index measures the performance of the small/mid cap companies located in the United States that also exhibit a growth probability. The Russell 2500 Value® Index measures the performance of the small/mid cap companies located in the United States that also exhibit a value probability. The volatility (beta) of the composite may be greater or less than the benchmarks. It is not possible to invest directly in these indices.

For more on Small Cap Equity, access the latest resources.

ARISTOTLE CAPITAL BOSTON, LLC

Markets Review

U.S. small cap equities delivered robust performance in the third quarter of 2025, with the Russell 2000 Index reaching its first all-time high since November 2021. The rally was driven by a generally favorable macroeconomic backdrop, including a 25 basis point rate cut by the Federal Reserve in September, which marked a shift toward more accommodative policy amid signs of labor market softening. U.S. GDP growth remained strong at 3.8% in Q2, supported by resilient consumer spending and the easing of trade tensions following tariff rollbacks. Inflation edged higher to 2.9%, driven in part by energy costs and tariff passthroughs, but remained within a manageable range for businesses and consumers. Sentiment was risk-on, fueled by Artificial Intelligence driven optimism as companies with AI exposure or disruptive potential saw disproportionate gains, as investors chased momentum and future earnings potential over traditional valuation metrics. Small caps benefited from dovish Fed rhetoric, attractive relative valuations, broadening of market breadth, earnings recovery and a rotation away from mega cap stocks.

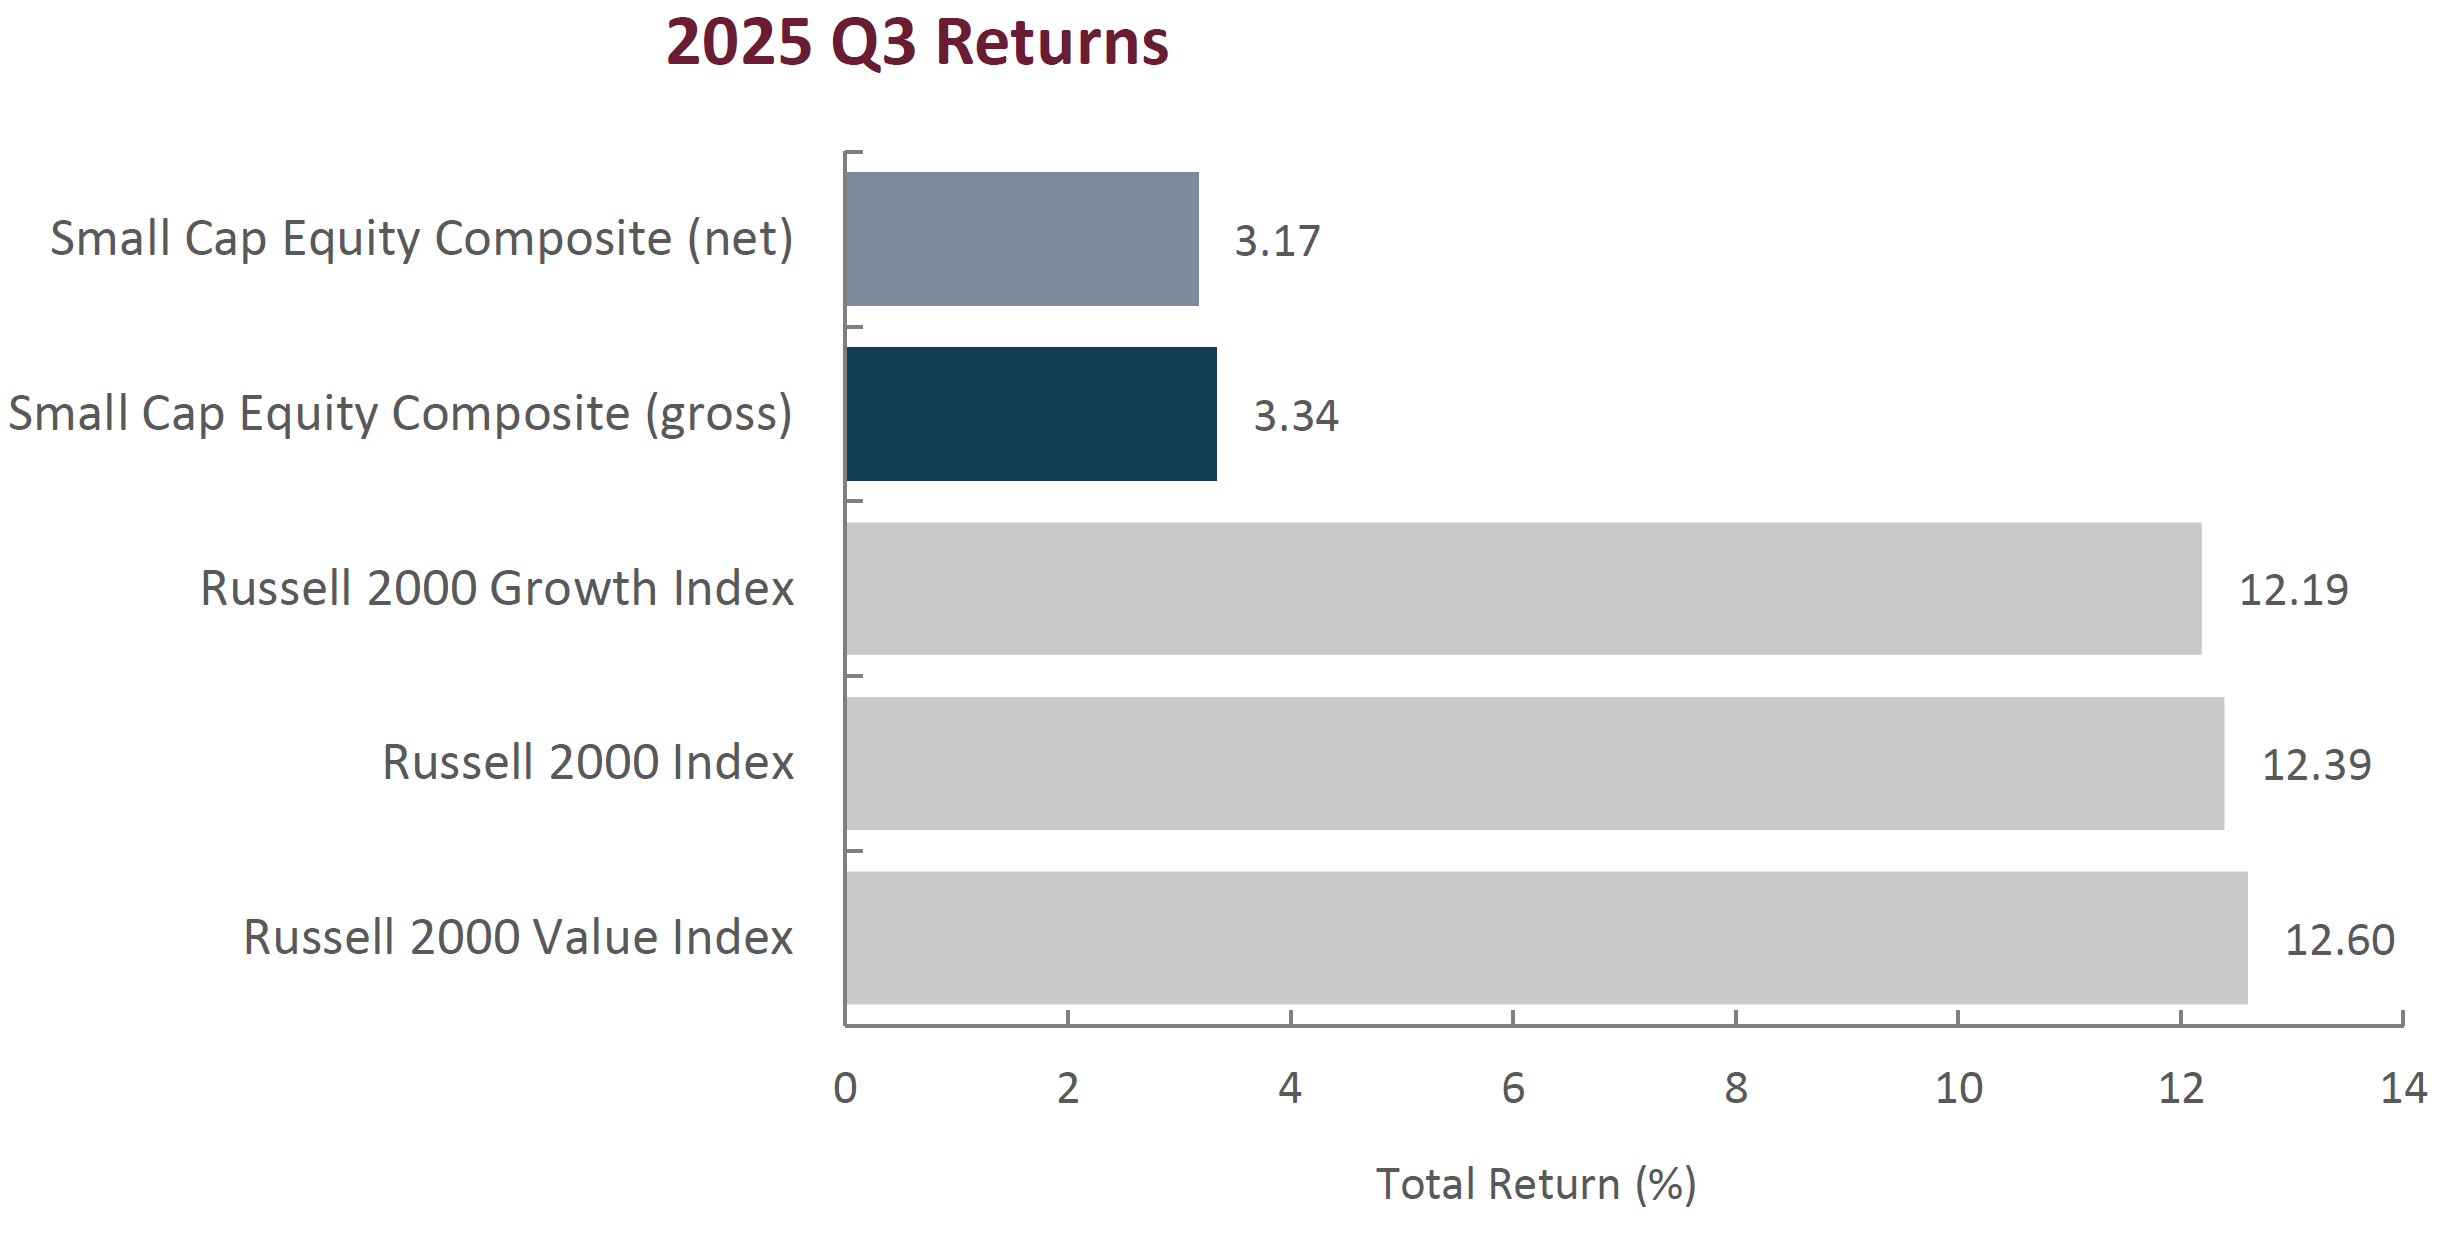
Stylistically, value stocks slightly outperformed their growth counterparts during the quarter as the Russell 2000 Value Index returned 12.60% compared to the 12.19% return of the Russell 2000 Growth index. This may be counterintuitive as growth factors mainly drove the market but the Russell 2000 Value Index’s financials sector weight (2.5x larger than the Russell 2000 Growth Index) significantly benefitted from the cut in interest rates.

From a factor perspective, lower quality companies significantly outperformed higher quality companies during the quarter. Factors that had the strongest payoffs were high beta, momentum, higher volatility, non-earners, high sales growth, micro caps, cyclical and highly shorted stocks.

At the sector level, cyclical stocks outperformed defensive stocks. The best performing sectors were Materials (+25.01%), Industrials (+16.56%), and Communication Services (+16.12%) while the worst performing sectors were Consumer Staples (+1.75%), Financials (+4.34%), and Real Estate (+6.95%).


Sources: CAPS Composite Hub, Russell Investments
Past performance is not indicative of future results. Returns are presented gross and net of investment advisory fees and include the reinvestment of all income. Gross returns will be reduced by fees and other expenses that may be incurred in the management of the account. Net returns are presented net of actual investment advisory fees and after the deduction of all trading expenses. Aristotle Small Cap Equity Composite returns are preliminary pending final account reconciliation. Please see important disclosures at the end of this document.

Performance Review

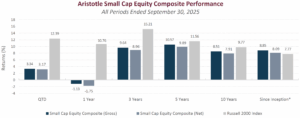
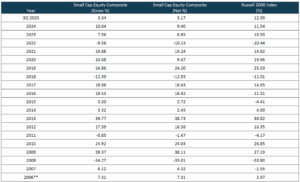
For the third quarter of 2025, the Aristotle Small Cap Equity Composite posted a total return of 3.17% net of fees (3.34% gross of fees), underperforming the 12.39% total return of the Russell 2000 Index. The largest detractor from relative performance was security selection in Industrials, Health Care (a combination of stocks we owned coupled with not owning biotechnology) and Information Technology (not owning quantum computing stocks and non-earning SaaS companies). This was partially offset by strong security selection in the Consumer Discretionary sector coupled with an underweight allocation to Financials and an overweight allocation to Materials.

Relative ContributorsRelative Detractors
Supernus PharmaceuticalsMACOM Technology Solutions
Mercury SystemsHaemonetics
Wolverine World WideSilgan Holdings
KnowlesJames Hardie Industries
Alamos GoldHealthEquity

CONTRIBUTORS

Supernus Pharmaceuticals (SUPN), is a Maryland-based specialty pharmaceutical company focused on developing drugs to treat Central Nervous System diseases. The stock benefitted from strong quarterly results, beating analyst expectations, alongside raising FY25 forecasts. We continue to maintain our position as we believe the company’s differentiated product pipeline, along with its existing neurology products, provides strong growth potential with attractive profitability and free cash flow generation capabilities.

Mercury Systems (MRCY), is a Massachusetts-based technology company focused on delivering processing technology for aerospace and defense missions including signal solutions, display, software applications, networking, storage, and secure processing. The company reported strong earnings, beating analyst expectations, and benefited from its strong position as a supplier to the defense sector. We believe the company will continue to benefit from increased national defense spending as well as revenue expected from their current $1.4B order backlog.

DETRACTORS

MACOM Technology Solutions (MTSI), is a designer and manufacturer of high-performance semiconductor products. Despite reporting strong Q3 earnings, the stock declined as investors reacted to a slight margin impact from a recent acquisition and a slower-than-expected recovery in the industrial market—both short-term deviations from analyst forecasts. We maintain our position, as we believe the company’s meaningful exposure to growing demand from Data Center and 5G end market applications along with the integration of recent acquisitions and domestic manufacturing footprint should drive additional shareholder value in periods to come.

Haemonetics (HAE), is a global provider of hematology and blood management products and solutions. The company delivered mixed results during the quarter, beating analyst earnings estimates but posting weaker than expected revenue results. We believe that the company’s strong competitive position within the plasmapheresis market along with increased investment in research and development should create value for shareholders over a multi-year period.

Recent Portfolio Activity

Buys/AcquisitionsSells/Liquidations
Columbia Banking System1-800-FLOWERS.COM
Dolby LaboratoriesALLETE
Hilton Grand VacationsAZEK
James Hardie IndustriesCarter’s
Knight-Swift Transportation HoldingsPacific Premier Bancorp
ONE GasRing Energy
Range ResourcesWabash National

BUYS/ACQUISITIONS

Columbia Banking System (COLB), is a Washington state based commercial bank that is in the early stages of winding down a large portfolio of low-yielding loans with organically driven higher yielding relationship loans and lower cost core deposit funding. A combination of operational cost savings associated with the Pacific Premier Bancorp merger and an increased focus on increasing fee-based income should allow for higher than historical profit margins and an attractive EPS growth outlook, ultimately allowing for incremental share buybacks or dividend increases.

Dolby Laboratories (DLB), develops and licenses proprietary audio-video technology to content creators, consumer electronics manufacturers, video streaming platforms and automotive manufacturers. Deeper market penetration of its Atmos and Vision technologies with more consumer electronics devices and increasing adoption by auto manufacturers are expected to drive higher margins over the next several years. The company’s capital efficient operating model yields attractive cash flow generation and returns on capital.

Hilton Grand Vacations (HGV), a leading global timeshare company that develops, markets and operates a system of brand-name, high-quality vacation ownership resorts in select vacation destinations, under the brand names: Hilton Vacation Club, Hilton Grand Vacation Club, Hilton Club. HGV’s proprietary relationship with Hilton Worldwide Holdings (HLT) allows it to market exclusively to HLT’s 180 mil Hilton Honors members to capitalize on growing demand for travel. Recent acquisitions broadened the company resort base to include properties appealing to higher income consumers.

James Hardie Industries (JHX), manufactures Fiber Cement and Fiber Gypsum products (siding, backerboard, etc.) used primarily in residential construction (newbuild and repair/remodel). JHX acquired the existing portfolio company, The AZEK Company (AZEK), which provides JHX with a broader product offering for distributors, contractors and homeowners, positioning the company for market share gains in an expanded addressable market. Operating synergies, merger cost synergies and enhanced scale efficiencies should further enhance the shareholder value creation potential.

Knight-Swift Transportation Holdings (KNX), is a North American-based transportation (truckload, less-than-truckload and intermodal) and logistics services provider. KNX is poised to benefit from an increase in freight transportation demand combined with subdued supply of transportation providers. A cyclical upturn in the freight cycle should drive increased revenues, earnings and cash flow, providing the company options to reinvest in the business or return capital to shareholders through share buybacks and/or a dividend increase.

ONE Gas (OGS), is an Oklahoma based, fully regulated gas utility company with service territories in Oklahoma, Kansas and Texas. The company has a proven track record of consistent rate base increases driven by population growth and infrastructure investments. A favorable regulatory backdrop in each of their service territories should allow for continued operational consistency and regular modest dividend increases, creating an attractive total return opportunity for the portfolio.

Range Resources (RRC), is a Texas based exploration and production company focused on extracting natural gas from the Marcellus Shale and Utica Shale formations within the Pennsylvania portion of the Appalachian Basin. The company’s large acreage position (800k Marcellus acres) provides a deep inventory (30+ yrs) of low-cost development locations that are expected to allow the company to capitalize on increased global demand for natural gas. Opportunities for increased drilling efficiencies should lower total operating costs, enhance earnings and drive greater cash flow generation that can be used to enhance shareholder value over the next several years.

SELLS/LIQUIDATIONS

1-800-FLOWERS.COM (FLWS), is an e-commerce provider of floral and gift products. The position was liquidated due to an increasingly uncertain fundamental outlook.

ALLETE (ALE), is a Minnesota based electric utility company. The position was liquidated ahead of its pending acquisition by a private equity consortium.

AZEK (AZEK), is a manufacturer of composite decking products for primarily residential applications. The company was acquired by James Hardie Industries plc (JHX).

Carter’s (CRI), is a manufacturer, distributor and retailer of infant and young children’s apparel. The position was liquidated due to deteriorated fundamental performance and an uncertain strategic outlook.

Pacific Premier Bancorp (PPBI), a California based bank holding company, was acquired by Columbia Banking System (COLB).

Ring Energy (REI), is an oil and gas exploration company, which engages in acquisition, exploration, development, and production activities. The position was liquidated due to the energy market outlook weakening thus delaying management’s strategic plan to scale through acquisitions and generate necessary operational efficiencies.

Wabash National (WNC), a manufacturer of dry freight and refrigerated semi-trailers, was liquidated due to uncertain fundamental outlook.

Outlook

We continue to remain optimistic about the long-term potential for the small-cap segment of the U.S. market. Valuations remain compelling relative to large caps, with the Russell 2000 Index trading near multi-decade lows on a relative basis. Potential tailwinds, including deregulation, lower corporate tax rates, increased M&A activity, continued reshoring of U.S. manufacturing, and infrastructure-related spending, could provide additional support for small-cap stocks. Volatility remains elevated over concerns around inflationary risks, geopolitical tensions, and potential U.S. economic and labor weakness.

Positioning

Our current positioning is a function of our bottom-up security selection process and our ability to identify what we view as attractive investment candidates, regardless of economic sector definitions. Overweight allocations in Information Technology and Industrials are mostly a function of our underlying company specific views rather than any top-down predictions for each sector. Conversely, we continue to be underweight in Consumer Discretionary, as we have been unable to identify what we consider to be compelling long-term opportunities that fit our discipline given the rising risk profiles of many retail businesses and a potential deceleration in goods spending following a period of strength. We are also underweight in Health Care as we do not hold Biotechnology companies as that industry has significant binary risk. Given our focus on long-term business fundamentals, our patient investment approach and low portfolio turnover, the strategy’s positioning generally does not change significantly from quarter to quarter. However, we may take advantage of periods of volatility by adding selectively to certain companies when appropriate.

Disclosures

The opinions expressed herein are those of Aristotle Capital Boston, LLC (Aristotle Boston) and are subject to change without notice.

Past performance is not indicative of future results. The information provided in this report should not be considered financial advice or a recommendation to purchase or sell any particular security. There is no assurance that any securities discussed herein will remain in an account’s portfolio at the time you receive this report or that securities sold have not been repurchased. The securities discussed may not represent an account’s entire portfolio and, in the aggregate, may represent only a small percentage of an account’s portfolio holdings. The performance attribution presented is of a representative account from Aristotle Boston’s Small Cap Equity Composite. The representative account is a discretionary client account which was chosen to most closely reflect the investment style of the strategy. The criteria used for representative account selection is based on the account’s period of time under management and its similarity of holdings in relation to the strategy. It should not be assumed that any of the securities transactions, holdings or sectors discussed were or will be profitable, or that the investment recommendations or decisions Aristotle Boston makes in the future will be profitable or equal the performance of the securities discussed herein. Aristotle Boston reserves the right to modify its current investment strategies and techniques based on changing market dynamics or client needs. Recommendations made in the last 12 months are available upon request.

Returns are presented gross and net of investment advisory fees and include the reinvestment of all income. Gross returns will be reduced by fees and other expenses that may be incurred in the management of the account. Net returns are presented net of actual investment advisory fees and after the deduction of all trading expenses.

Effective January 1, 2022, the Aristotle Small Cap Equity Composite has been redefined to exclude accounts with meaningful industry-specific restrictions or substantial values-based screens hampering implementation of the small cap strategy.

All investments carry a certain degree of risk, including the possible loss of principal. Investments are also subject to political, market, currency and regulatory risks or economic developments. International investments involve special risks that may in particular cause a loss in principal, including currency fluctuation, lower liquidity, different accounting methods and economic and political systems, and higher transaction costs. These risks typically are greater in emerging markets. While Large-capitalization companies may have more stable prices than smaller, less established companies, they are still subject to equity securities risk. In addition, large-capitalization equity security prices may not rise as much as prices of equity securities of small-capitalization companies. Securities of small- and medium-sized companies tend to have a shorter history of operations, be more volatile and less liquid. Value stocks can perform differently from the market as a whole and other types of stocks. The material is provided for informational and/or educational purposes only and is not intended to be and should not be construed as investment, legal or tax advice and/or a legal opinion. Investors should consult their financial and tax adviser before making investments. The opinions referenced are as of the date of publication, may be modified due to changes in the market or economic conditions, and may not necessarily come to pass. Information and data presented has been developed internally and/or obtained from sources believed to be reliable. Aristotle Boston does not guarantee the accuracy, adequacy or completeness of such information.

Aristotle Capital Boston, LLC is an independent investment adviser registered under the Investment Advisers Act of 1940, as amended. Registration does not imply a certain level of skill or training. More information about Aristotle Boston, including our investment strategies, fees and objectives, can be found in our Form ADV Part 2, which is available upon request. ACB-2510-17

Performance Disclosures

Sources: CAPS Composite Hub, Russell Investments

Composite returns for periods ended September 30, 2025, are preliminary pending final account reconciliation.

*The Aristotle Small Cap Equity Composite has an inception date of November 1, 2006, at a predecessor firm. During this time, Jack McPherson and Dave Adams had primary responsibility for managing the strategy. Performance starting January 1, 2015, was achieved at Aristotle Boston.

**For the period November 2006 through December 2006.

Past performance is not indicative of future results. Performance results for periods greater than one year have been annualized.

Effective January 1, 2022, the Aristotle Small Cap Equity Composite has been redefined to exclude accounts with meaningful industry-specific restrictions or substantial values-based screens hampering implementation of the small cap strategy.

Returns are presented gross and net of investment advisory fees and include the reinvestment of all income. Gross returns will be reduced by fees and other expenses that may be incurred in the management of the account. Net returns are presented net of actual investment advisory fees and after the deduction of all trading expenses. Please see important disclosures enclosed within this document.

Index Disclosures

The Russell 2000® Index measures the performance of the small cap segment of the U.S. equity universe. The Russell 2000 Index is a subset of the Russell 3000® Index. It includes approximately 2,000 of the smallest securities based on a combination of their market capitalization and current index membership. The Russell 2000 Growth® Index measures the performance of the small cap companies located in the United States that also exhibit a growth probability. The Russell 2000 Value® Index measures the performance of the small cap companies located in the United States that also exhibit a value probability. The volatility (beta) of the composite may be greater or less than the benchmarks. It is not possible to invest directly in these indices.
For more on Small Cap Equity, access the latest resources.

The last decade has been a story of large cap outperformance. Since December 2004, the Russell 3000 Index has grown nearly five-fold, largely on the strength of the large cap companies in the Russell 1000 Index. The market capitalization of the next two thousand companies in the Index has fallen from a high of 10.8% in the spring of 2006 to a twenty-year low of 4.6% in the summer of 2025. You can make the argument that large cap stocks are expensive or that U.S. small caps are cheap. We will focus on the latter, with small cap valuations low versus their larger peers as well as against their own history. Starting at a low in valuations and weaving in multiple tailwinds that could support small cap performance in the years ahead, we believe now may be the time for investors to take a second look.

To read the full thought piece, please use the link below.

Air Date July 28, 2025

Aristotle Pacific’s Jeffrey Klingelhofer, CFA,   was live on Schwab Network’s “Market on Close” with Marley Kayden. In this segment, he discusses the evolving Fed narrative and shifting rate expectations to what these developments could mean for investors navigating today’s complex market environment.   

Watch the full interview below.

Jeff Klingelhofer
Managing Director, Portfolio Manager


About Aristotle Pacific
Aristotle Pacific Capital is a Newport Beach, Calif.-based registered investment adviser that actively invests in credit securities on the basis of fundamental credit analysis with the objective of identifying and realizing relative value. The firm manages credit strategies across floating-rate loans, CLOs, multi-sector, high-yield, investment-grade, and short-duration bonds.

Learn More About Aristotle Pacific

For more Resources from Aristotle, contact us.

The Latin word cultellus (in Italian, coltello) generally means “smaller knife” or “dagger.”  It is a common Latin root for several Italian and French words that, today, refer to small swords.  As well, it is the origin of the English word cutlery.

Cultellus became coutelas, a 16th-century French word for a mid-length single-edged blade.  A coutelas then became a cutlass, a 17th-century English abbreviated sword.  This tool (or weapon, depending upon its use) has a short and more or less curved single-edged blade.  The grip is generally of wood, but some specimens show a brass grip with spiral grooves, the fancier ones perhaps adorned with stones.  The length of the blade is usually about twenty-four inches.

To read the full article, please use the link below.