

Research
Patience Powered by Fundamental Research
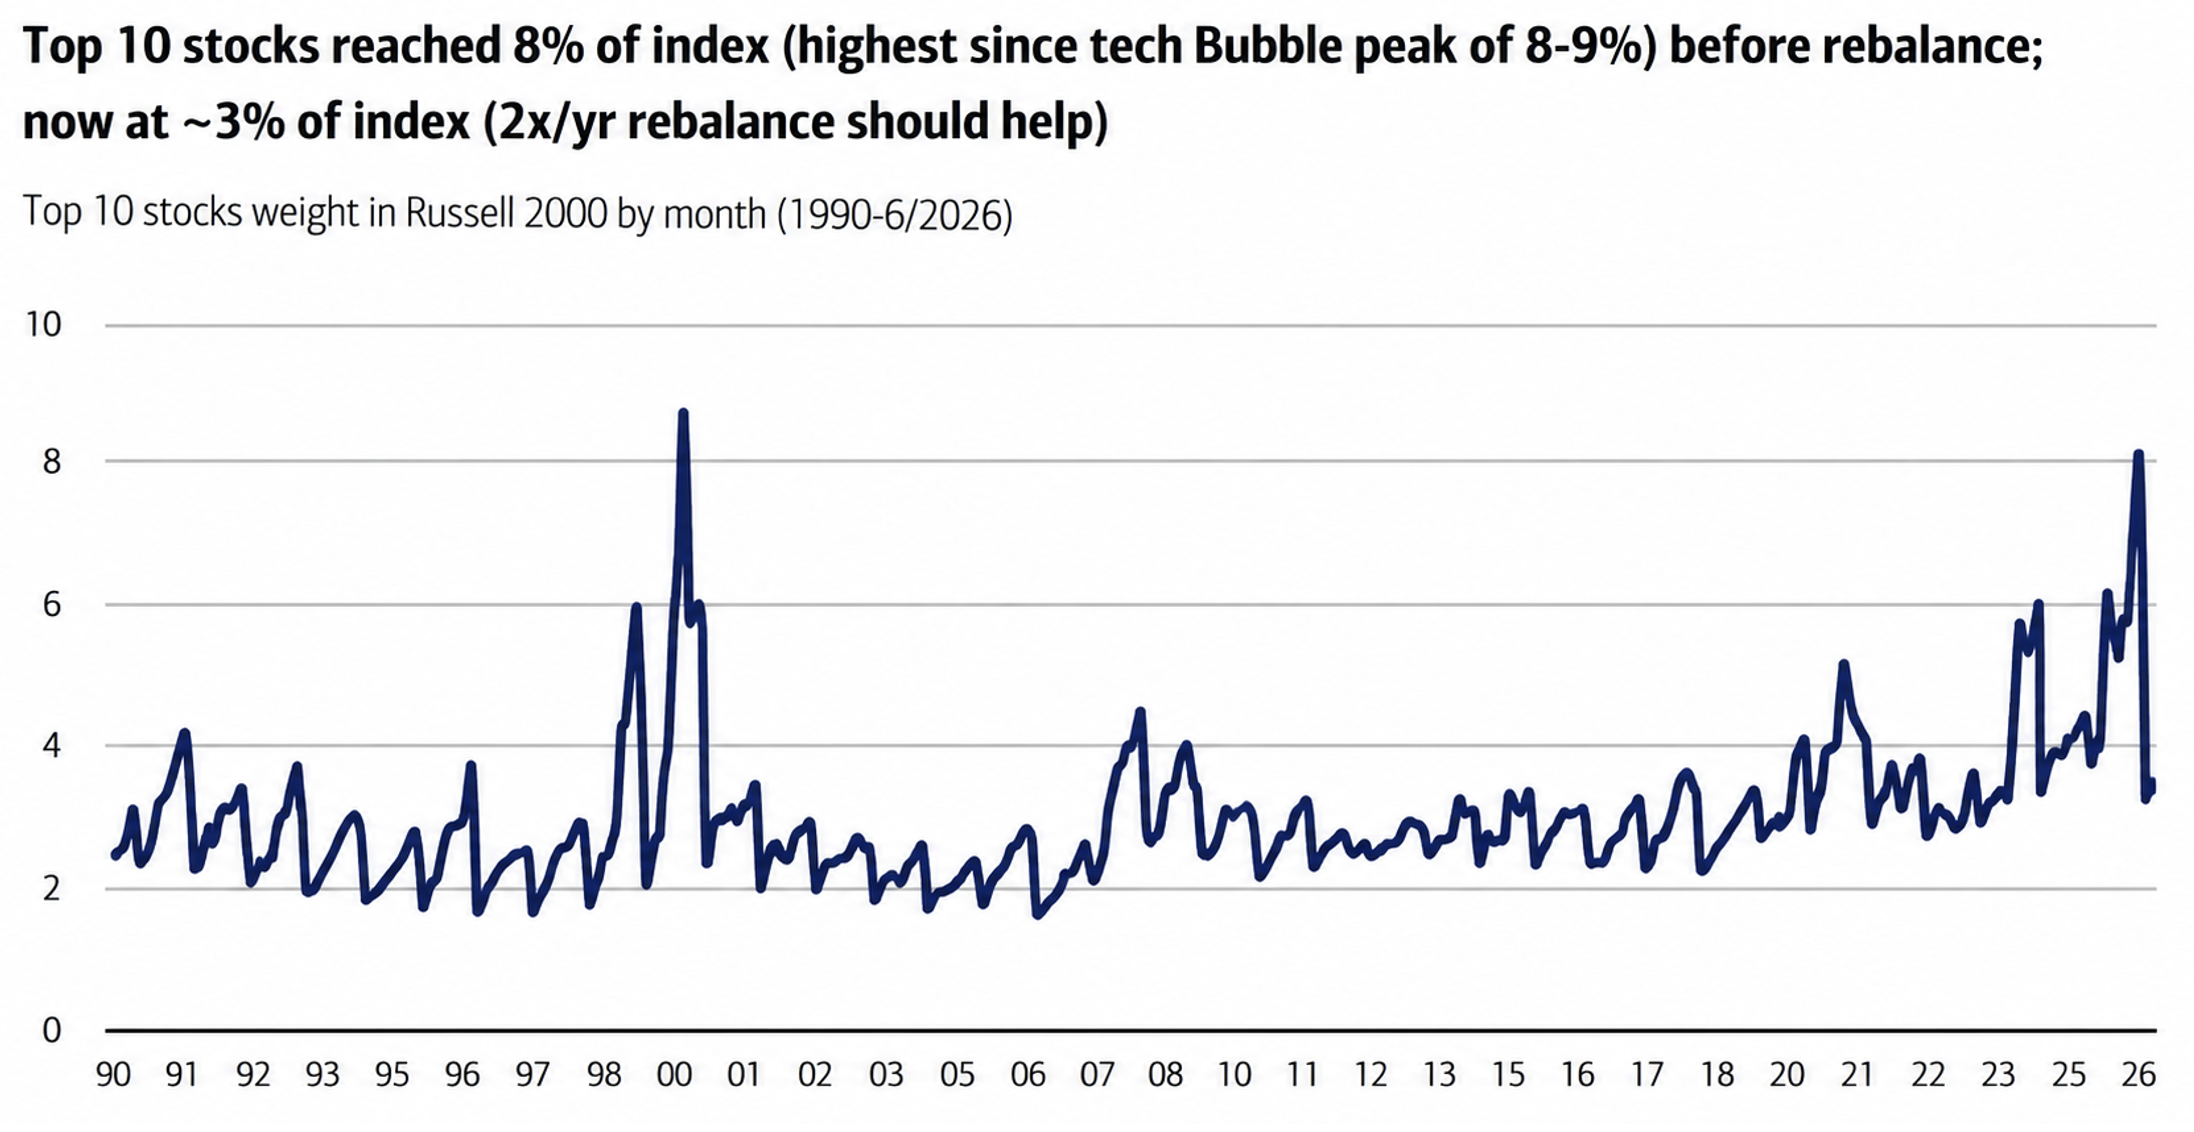
The Magnificent 7 made index concentration a familiar large cap story. Increasingly, concentration is shaping the small cap market as well.
Historically, the Russell 2000 was relatively insulated from this dynamic. Since the pandemic, that has begun to change and the second quarter of 2026 offered a striking example:
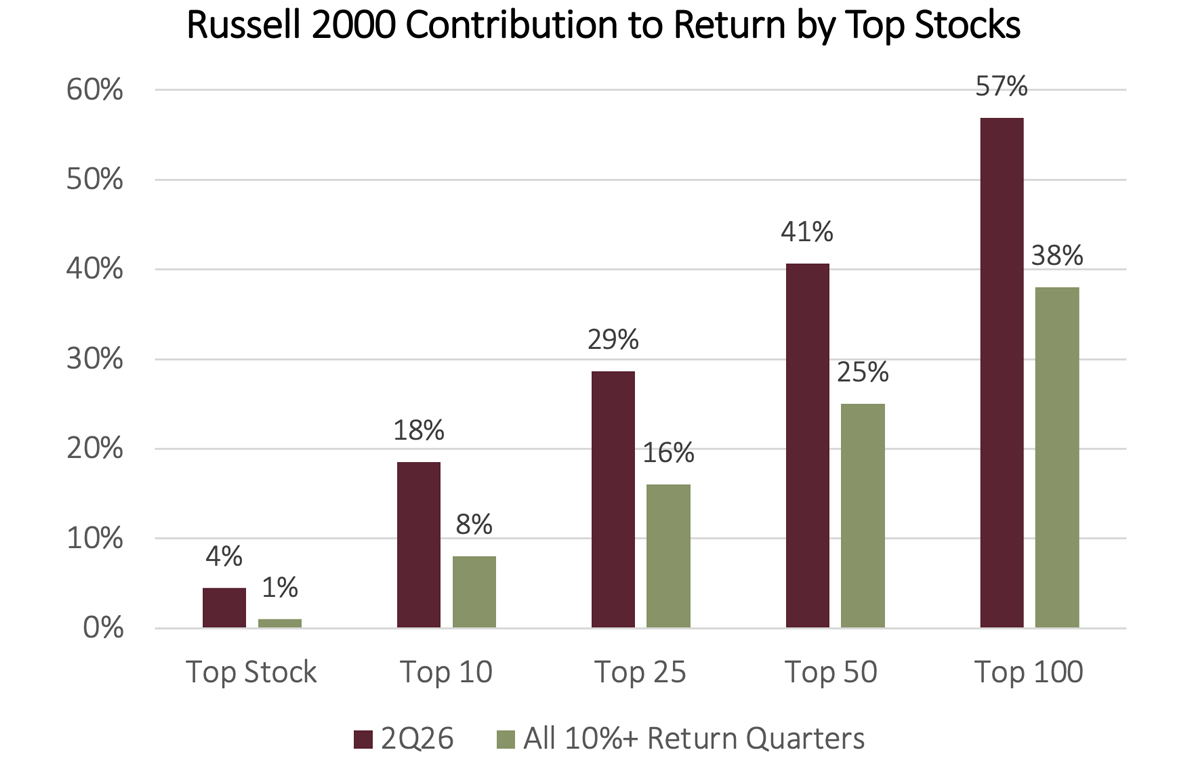
- The index’s top 25 stocks accounted for almost twice their historical average contribution during quarters when the Russell 2000 gained 10% or more.
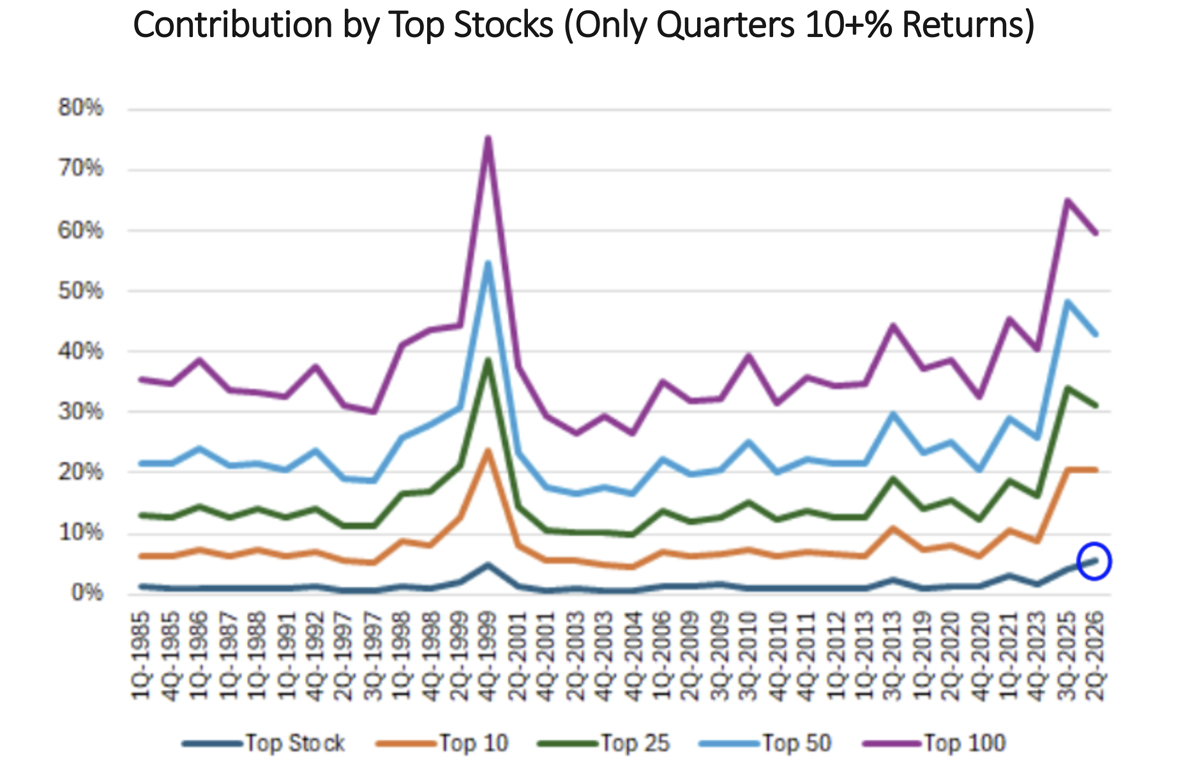
- The quarter was the third-most concentrated among the Russell 2000’s strongest quarters, trailing only the fourth quarter of 1999 and the third quarter of 2025.
- Bloom Energy delivered the largest single stock contribution of any quarter in which the index returned at least 10%.
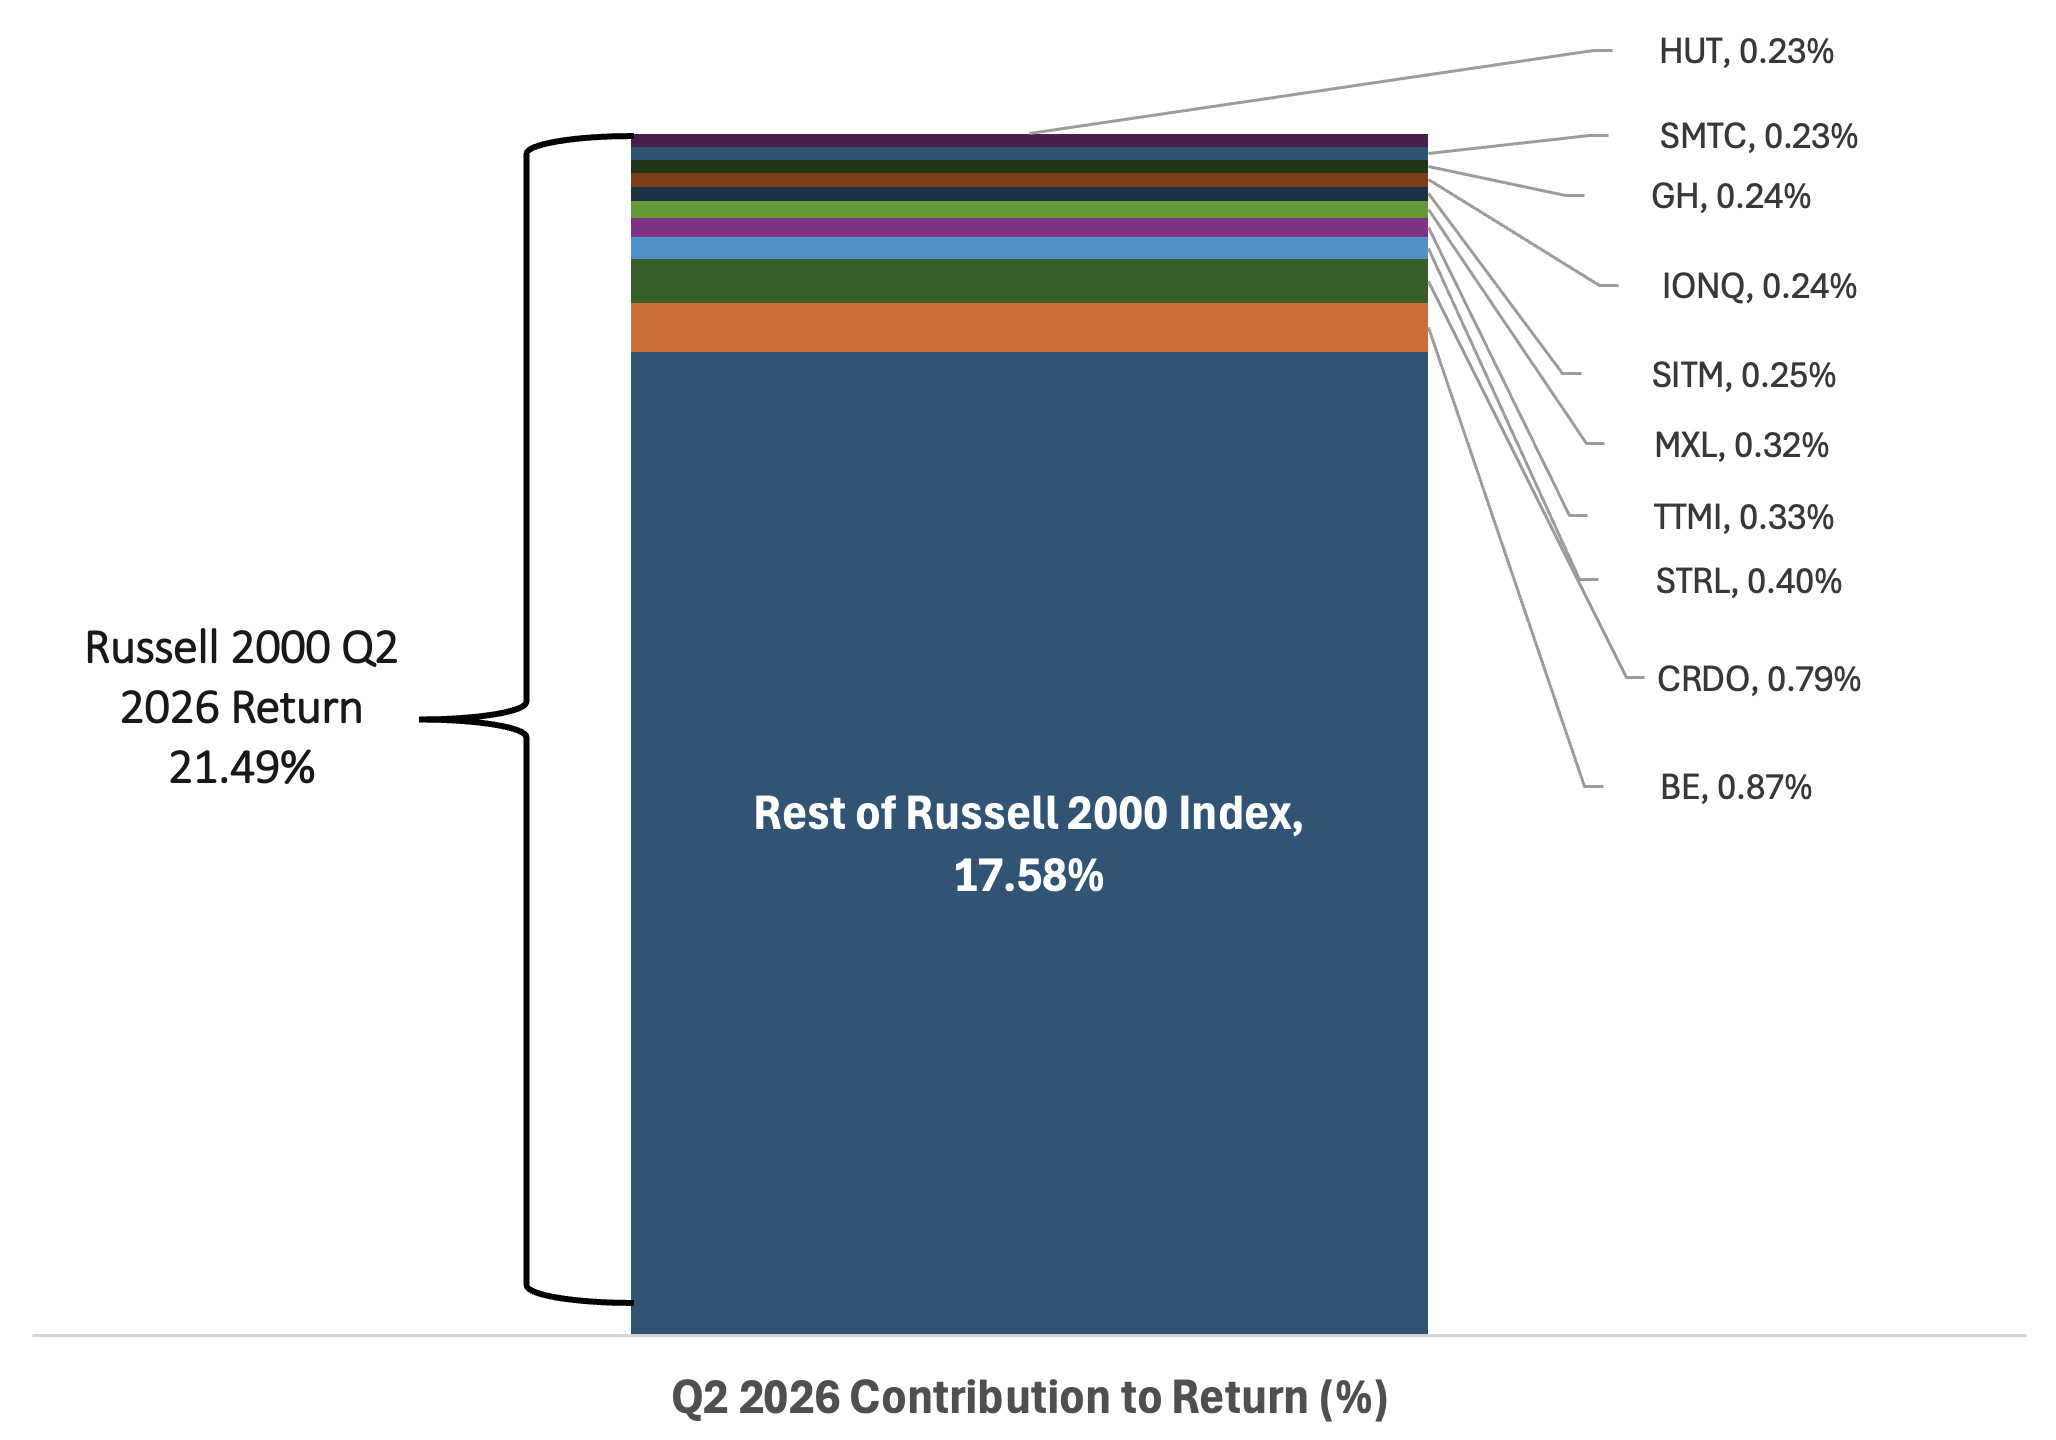
- Just 10 stocks generated 18% of the Russell 2000’s total quarterly return.
The Russell reconstitution process, and the shift to a semiannual schedule, should help refresh index membership more frequently and reduce the potential impact of excessive security level concentration over time.
For active managers, a more frequently refreshed and broadly representative benchmark may provide a healthier environment for fundamental research and security selection to be reflected in relative performance, rather than results being disproportionately dictated by a handful of index constituents.
The broader takeaway: headline index returns do not always tell the full story. Understanding what is driving those returns, and how broadly they are distributed, remains essential.
Explore our small caps observations for deeper insight.
2Q26 Russell 2000 Return Concentration 2Q26
2Q26 returns were highly concentrated in the Russell 2000’s top stocks with the Top 25, Top 10, and top stock accounting twice or more the average for quarters in which the index returned 10% or more.
2Q26 was the 3rd most concentrated among the Russell 2000’s best quarters, trailing only 4Q99 and 3Q25. The top stock (Bloom Energy) was the highest single contribution across all quarters in which the index returned 10% or more.
Source: Furey Research Partners, FactSet; as of 6/30/2026.
Russell 2000 Return Concentration 2Q26
18% of the Russell 2000’s 2Q26 return came from its top 10 stocks
Source: Furey Research Partners, FactSet; data as of 6/30/2026.
Russell 2000 Index Reconstitution
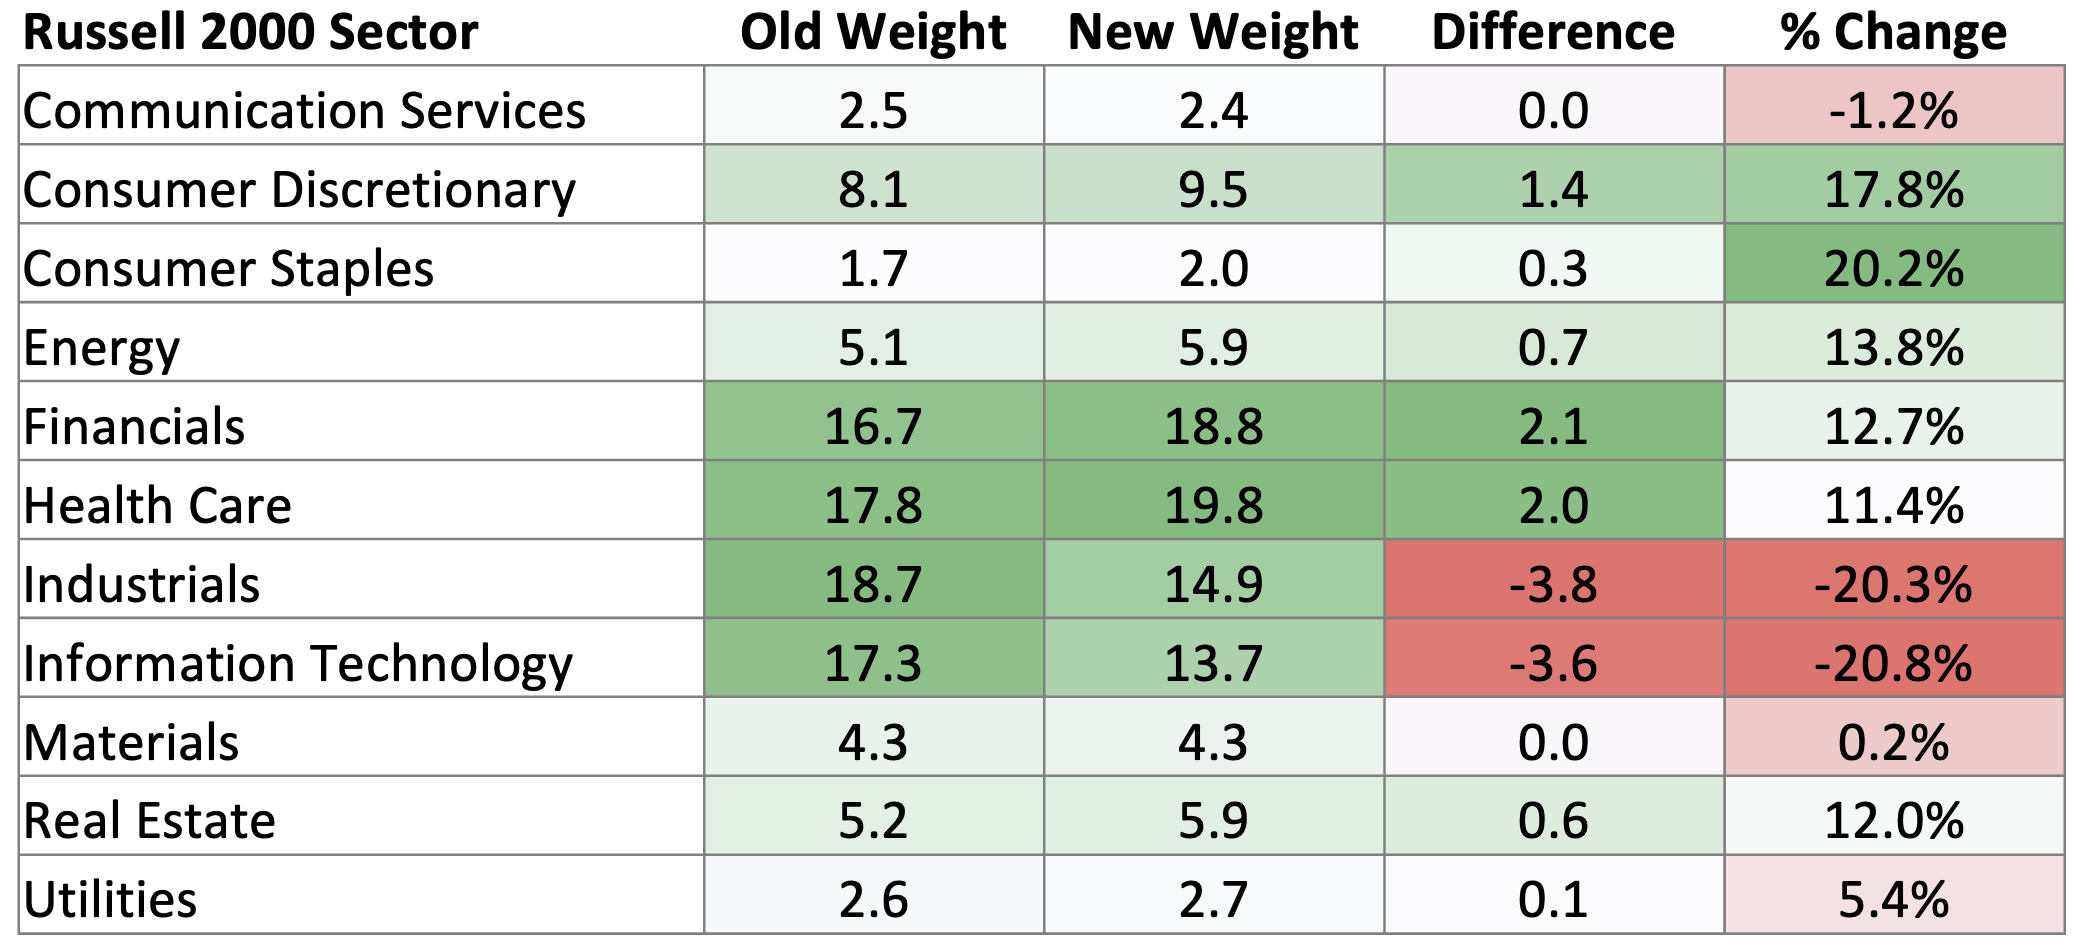
Reconstitution resulted in greater Health Care and Financials weights, while weight declined in the Industrials and Information Technology sectors.
Source: Furey Research Partners, FactSet as of 6/30/2026.
For more small caps observations click here.
The opinions expressed herein are those of Aristotle Capital Boston (Aristotle Boston) and are subject to change without notice. This material is not financial advice or an offer to purchase or sell any product. Aristotle Boston reserves the right to modify its current investment strategies and techniques based on changing market dynamics or client needs.
All investments carry a certain degree of risk, including the possible loss of principal. Investments are also subject to political, market, currency and regulatory risks or economic developments. International investments involve special risks that may in particular cause a loss in principal, including currency fluctuation, lower liquidity, different accounting methods and economic and political systems, and higher transaction costs. These risks typically are greater in emerging markets. Securities of small- and medium-sized companies tend to have a shorter history of operations, be more volatile and less liquid. Value stocks can perform differently from the market as a whole and other types of stocks. The material is provided for informational and/or educational purposes only and is not intended to be and should not be construed as investment, legal or tax advice and/or a legal opinion. Investors should consult their financial and tax adviser before making investments. The opinions referenced are as of the date of publication, may be modified due to changes in the market or economic conditions, and may not necessarily come to pass. Information and data presented has been developed internally and/or obtained from sources believed to be reliable. Aristotle Boston does not guarantee the accuracy, adequacy or completeness of such information.
Past performance is not indicative of future results. The information provided in this report should not be considered financial advice or a recommendation to purchase or sell any particular security.
Differing historical time periods are selected throughout the presentation as we believe specific periods provide the most informative historical analog for the concepts presented.
The Russell 2000® Index measures the performance of the small cap segment of the U.S. equity universe. The Russell 2000 Index is a subset of the Russell 3000® Index representing approximately 10% of the total market capitalization of that index. It includes approximately 2000 of the smallest securities based on a combination of their market cap and current index membership. The volatility (beta) of the portfolios may be greater or less than the benchmark. It is not possible to invest directly in this index.
The S&P 500® Index is the Standard & Poor’s Composite Index and is a widely recognized, unmanaged index of common stock prices. It is market cap-weighted and includes 500 leading companies, capturing approximately 80% coverage of available market capitalization.
Aristotle Capital Boston, LLC is an independent investment adviser registered under the Investment Advisers Act of 1940, as amended. Registration does not imply a certain level of skill or training. More information about Aristotle Boston, including our investment strategies, fees and objectives, can be found in Form ADV Part 2, which is available upon request. ACB-2608-6